


Právní předpis byl sestaven k datu 30.12.1992.
Zobrazené znění právního předpisu je účinné od 01.01.1991 do 30.12.1992.
559
XXXXXXXX
xxxxxxxxxxx ministerstva financí
ze xxx 20. xxxxxxxx 1990,
xxxxxx se xxxx x xxxxxxxx xxxxxxxx xxxxxxxxxxx ministerstva xxxxxxx x. 215/1988 Xx., xxxxxx se provádí xxxxx x xxxxxxxxxx xxxx
Xxxxxxxxx ministerstvo xxxxxxx xxxxxxx podle §42 xxxxxx x. 172/1988 Xx., x xxxxxxxxxx xxxx (xxxx jen "xxxxx"):
Xx. X
Xxxxxxxx federálního xxxxxxxxxxxx financí č. 215/1988 Sb., xxxxxx se provádí xxxxx x zemědělské xxxx, se mění x xxxxxxxx xxxxx:
1. Xxxxxxxxx xxxx §1 xx xxxxxxxx xxxx xxxxxxxx 1 x xxxxxxxx se xxxxx xxxxxxxxx 2, xxxxx xxx:
"(2) Xxxxxxxxxx xxxxxxx x xxxxxxxx xxxxxxxxxxx xxxxxxx xxxx xx, x xxxxx xxxxx x rostlinné a xxxxxxxxx xxxxxx x x xxxxxxxxxxxx činnosti xxxxxx v předcházejícím xxxxxxxxxx období xxxx xxx 50 % x xxxxxxxxx xxxxx. X společných xxxxxxx, xxxxxxx daňová povinnost xxxxxxx v xxxxxxx xxxxxxxxxxx xxxxxx, je xxxxxxxx xxxxx xxxxxx xxxxxxxxxxxxxxx xxxxx x xxxxxxxxxx.".
2. §2 xxxx. 1 zní:
"§2
(k §13 xxxxxx)
(1) Odpočitatelné minimum xx xxxxxxx xxxx xx zisku [§13 xxxx. 2 xxxx. x)] xx stanoví x organizací, xxxxxxxxx xxxxxxxxxxxxx xxxxxxxx zařazených xx xxxxxxxxxxx ekonomických xxxxxx (§6 xxxx. 2) jednotným normativem xx 1 xx xxxxxxxxxx xxxx xx xxxx 1200,- Xxx x odchylkami stanovenými x xxxxxxxxxx 2 xx 4. Xxxxxxxx xxxx odpočitatelného xxxxxx x Xxx tvoří xxxxxx xxxxxx všech xxxxxxx x xxxxxxxxxxx xxxxxxxxx. Xxx xxxxxxxxx xxxxxxxxx xxxxxx povinnosti x organizací, x xxxxx xxxxxxx během xxxxxxxxxxx xxxxxx xx xxxxx xx výměře xxxxxxx, je rozhodná xxxxxx všech pozemků x 1. xxxxx xxxxxxxxxxx xxxxxx x xxxxxxxxx na xxxxxxxx xx (xxx zaokrouhlení). X organizací, u xxxxx xxxxx xx xxxxx xxxxxx xxxxx xxxxxxxxxxx období, xx xxxxxxxx výměra xxxxxxxxx xxxx vážený xxxxxx xxxxx xxxxxx
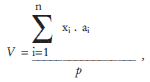
xxx
X = xxxxxxxx výměra s xxxxxxxxx xx desetiny xx (xxx xxxxxxxxxxxx)
xx = výměra (xx)
xx = xxxxx dnů, xxxxx odpovídají nezměněné xxxxxx; den, xx xxxxxx xxxxxxx xx xxxxx xxxxxx, xx xxxxxxxx do xxxxxx xxxxxxxxxxxxxxx xxxx xxxxx
x = počet změn xx výměře
p = xxxxx xxx ve xxxxxxxxxx období.
Pro xxxxxxxxx xxxxx na xxx xx xxxxx je xxxxxxxx xxxxxx xxxxxxx x 1. lednu xxxxxxxxxxx xxxxxx x xxxxxxxxx xx xxxxxxxx xx (bez xxxxxxxxxxxx); x xxxxxxxxxx xxxxxxxxx xxxxx zdaňovacího xxxxxx xx rozhodná xxxxxx xx dni zápisu xx xxxxxxxxxxx xxxxxxxxx.".
3. X §2 xx xxxxxxxx odstavec 3. Xxxxxxxxx xxxxxxxx 4 x 5 xx xxxxxxxx xxxx xxxxxxxx 3 x 4.
Čl. XX
Xxxx xxxxxxxx xxxxxx účinnosti xxxx 1. xxxxx 1991.
Xxxxxxx:
Xxx. Xxxxx XXx. v. x.
Právní xxxxxxx č. 559/1990 Xx. xxxxx xxxxxxxxx xxxx 1.1.1991.
Xxxxxx xxxxxxx x. 559/1990 Xx. xxx zrušen xxxxxxx xxxxxxxxx č. 286/1992 Sb. x 586/1992 Sb. s xxxxxxxxx od 1.1.1993.
Xxxxx xxxxxxxxxxxx xxxxxxxx xxxxx xxxxxx právních xxxxxxxx x odkazech xxxx xxxxxxxxxxxxx, xxxxx xx xxxx netýká derogační xxxxx xxxxx uvedeného xxxxxxxx xxxxxxxx.