


Právní předpis byl sestaven k datu 14.09.2021.
Zobrazené znění právního předpisu je účinné od 14.09.2021 do 31.12.2021.
Vyhláška o formulářových podáních pro daně z příjmů
525/2020 Sb.
Předmět úpravy §1
Vzory formulářových podání §2
Formulářové podání podané elektronicky §3
Formát formulářového podání §4
Společná ustanovení §5
Přechodná ustanovení §6
Účinnost §7
Příloha č. 1 - Přiznání k dani z příjmů fyzických osob pro poplatníky mající pouze příjmy ze závislé činnosti ze zdrojů na území České republiky (včetně daňových nerezidentů České republiky)
Příloha č. 2 - Přiznání k dani z příjmů fyzických osob
Příloha č. 3 - Vyúčtování daně z příjmů ze závislé činnosti
Příloha č. 4 - Vyúčtování daně vybírané srážkou podle zvláštní sazby daně z příjmů fyzických / právnických osob
Příloha č. 5 - Přiznání k dani z příjmů právnických osob
Příloha č. 6 - Hlášení plátce daně o provedení srážky ze zajištění daně ze zdanitelných příjmů
Příloha č. 7 - Přihláška k registraci pro fyzické osoby
Příloha č. 8 - Přihláška k registraci pro právnické osoby
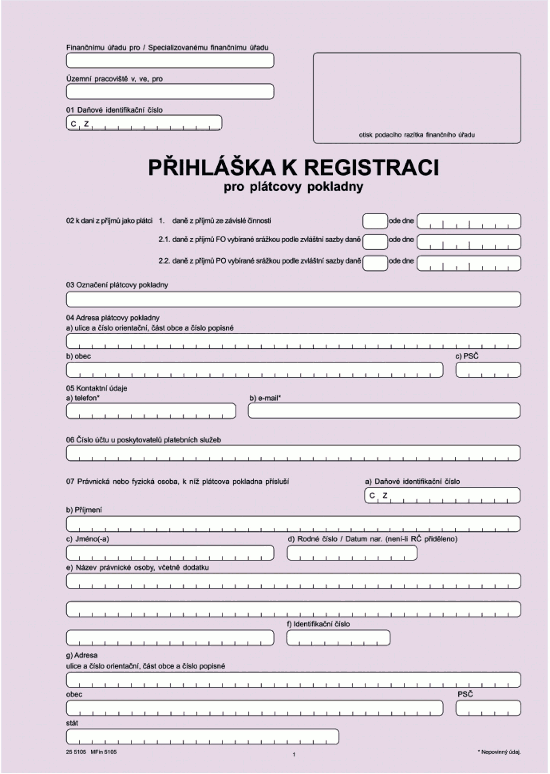
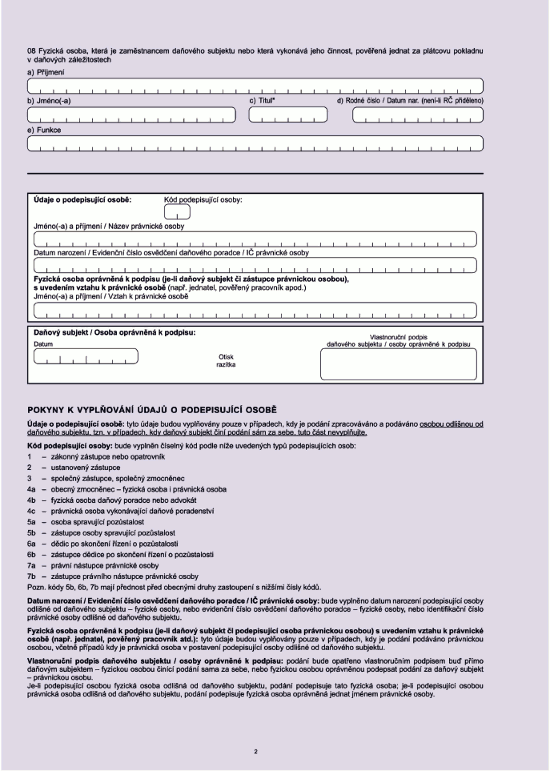
Příloha č. 9 - Přihláška k registraci pro plátcovy pokladny
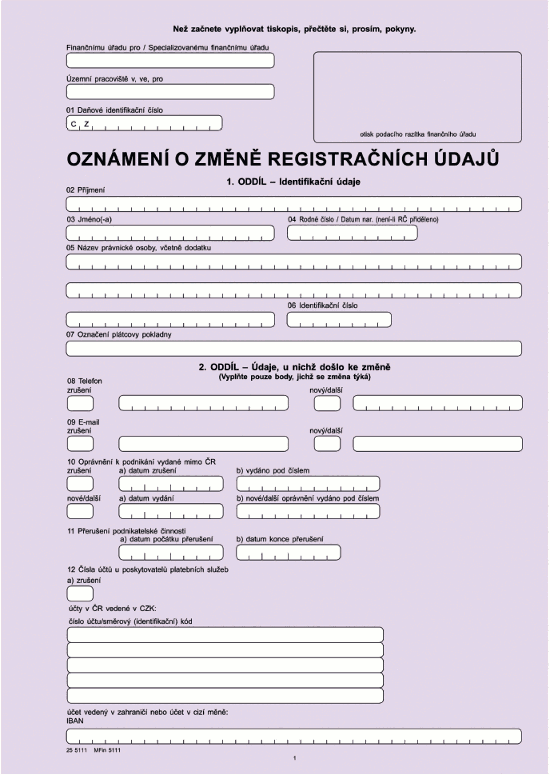
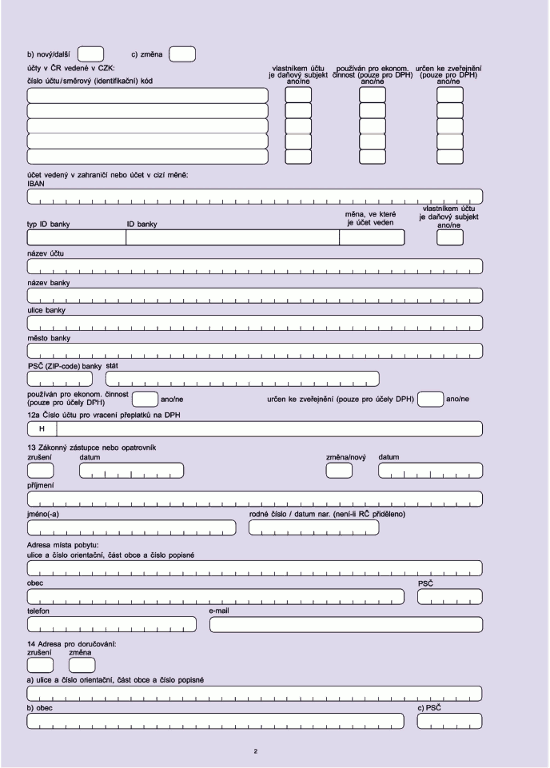
Příloha č. 10 - Oznámení o změně registračních údajů
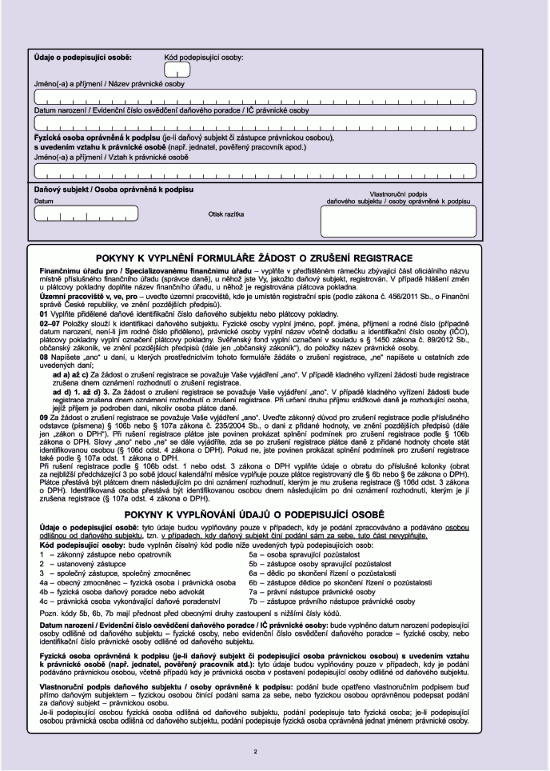
Příloha č. 11 - Žádost o zrušení registrace
č. 335/2021 Sb. - Čl. II
525
VYHLÁŠKA
ze dne 7. xxxxxxxx 2020
x xxxxxxxxxxxxx xxxxxxxx xxx daně x xxxxxx
Xxxxxxxxxxxx financí xxxxxxx xxxxx §72 xxxx. 4 x 5 xxxxxx č. 280/2009 Xx., daňový xxx, xx xxxxx xxxxxx x. 283/2020 Xx.:
§1
Předmět xxxxxx
Xxxx xxxxxxxx xxxxxxx v případě xxxxxxxxxxxxx podání pro xxxx z xxxxxx
x) xxxxxxxxxxx xxxxxxxx xxxxxxxxxxx xxxxxx a xxxxxxxxxxxx xxxxx,
x) formát xxxxxxxxxxxxxx xxxxxxxxxxxxx xxxxxx x
x) xxxx xxxxxxxxxxxxx xxxxxx.
§2
Xxxxx xxxxxxxxxxxxx xxxxxx
(1) Xxxx
x) xxxxxxxx k xxxx x xxxxxx xxxxxxxxx xxxx xxx xxxxxxxxxx xxxxxx xxxxx xxxxxx xx závislé xxxxxxxx xx xxxxxx xx xxxxx Xxxxx xxxxxxxxx (včetně xxxxxxxx xxxxxxxxxxx České republiky) xx xxxxxx x příloze č. 1 k xxxx xxxxxxxx,
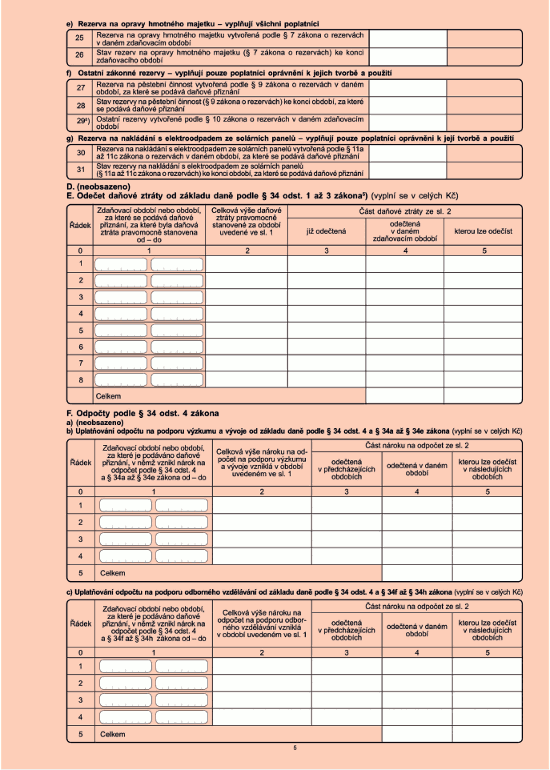
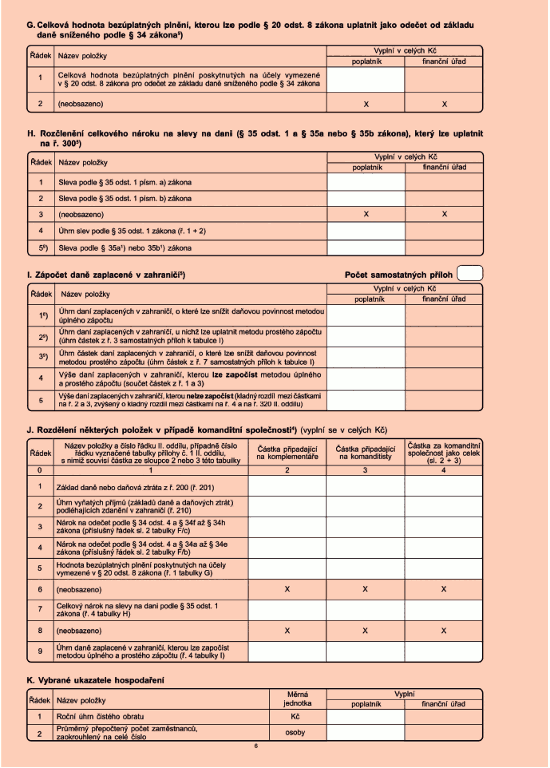
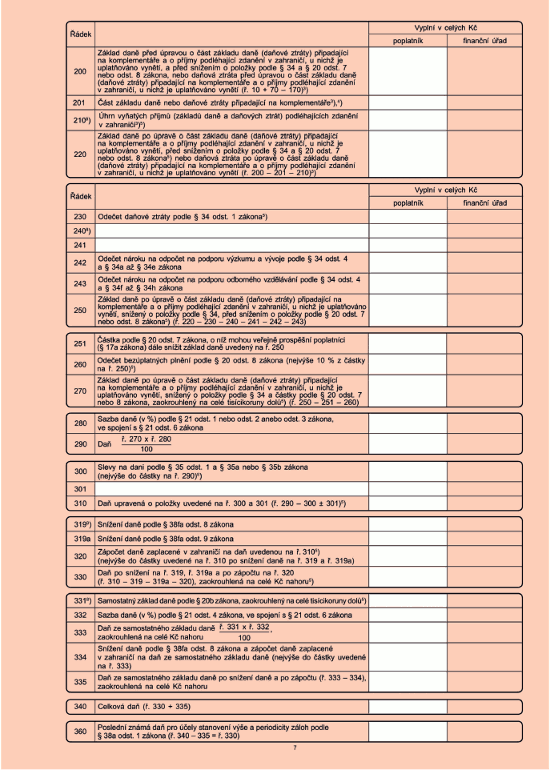
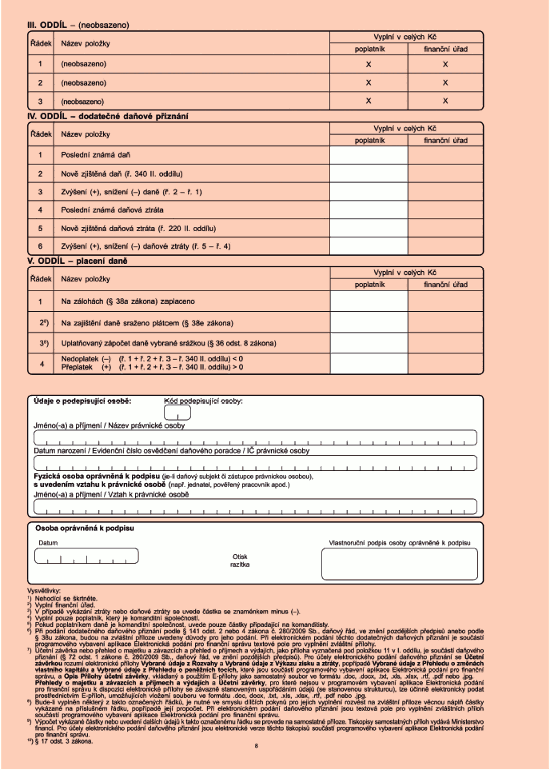
x) přiznání x xxxx x xxxxxx xxxxxxxxx osob xx xxxxxx v příloze č. 2 x xxxx xxxxxxxx,
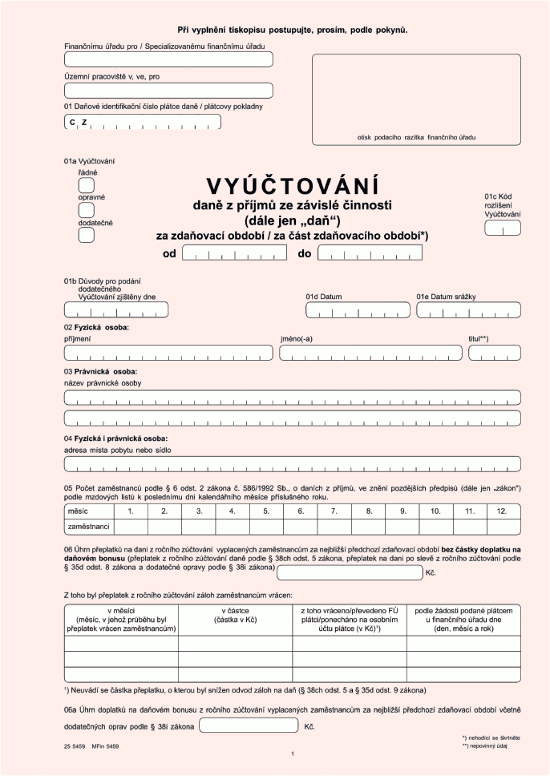
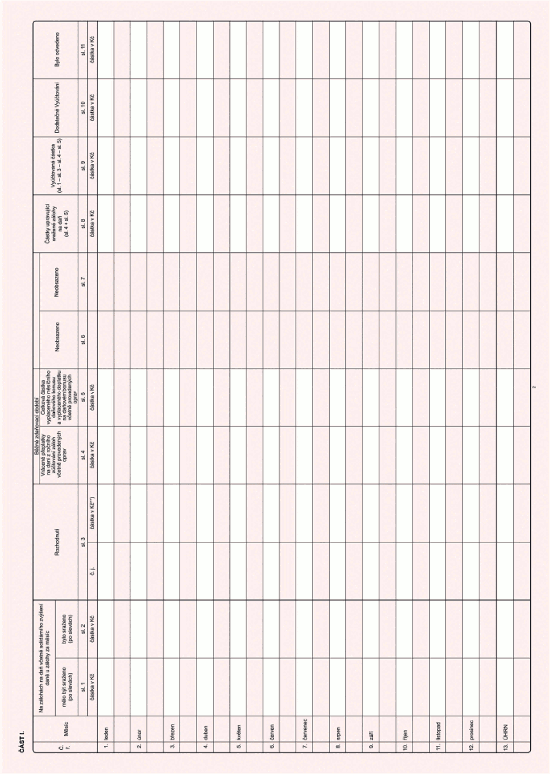
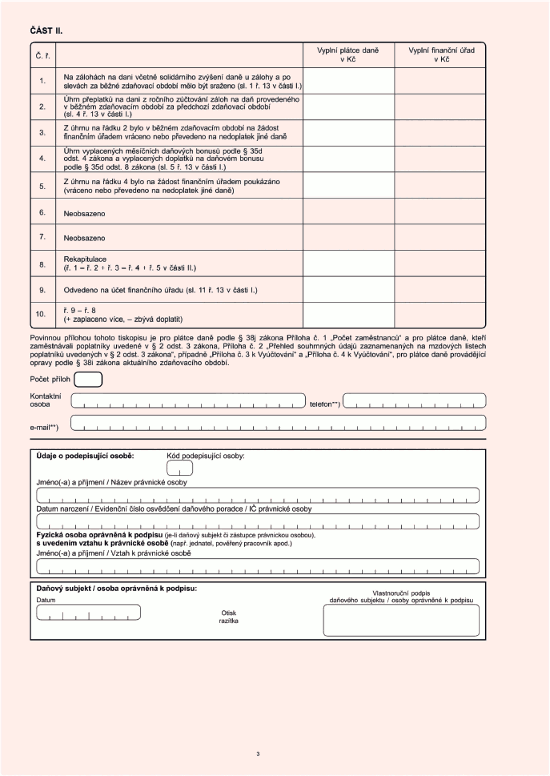
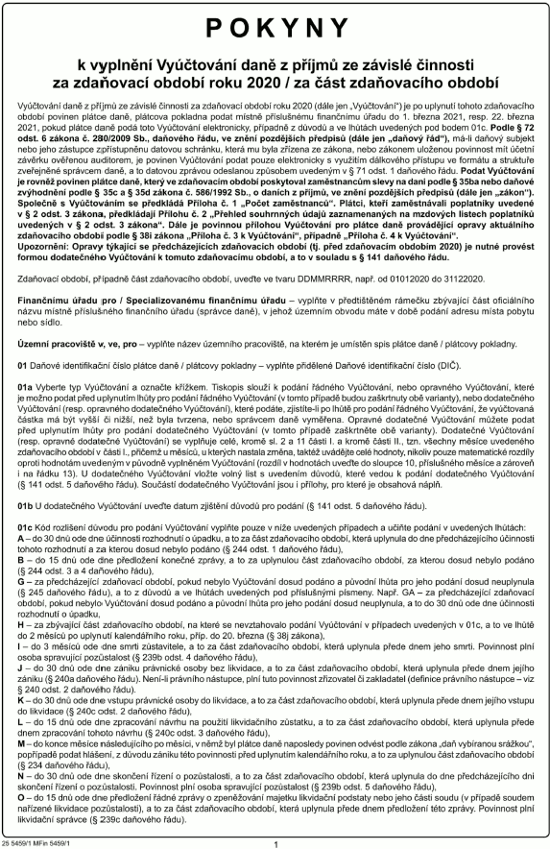
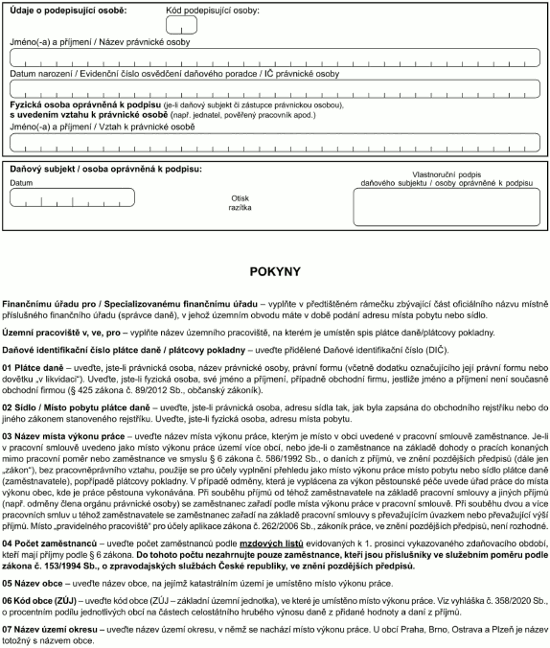
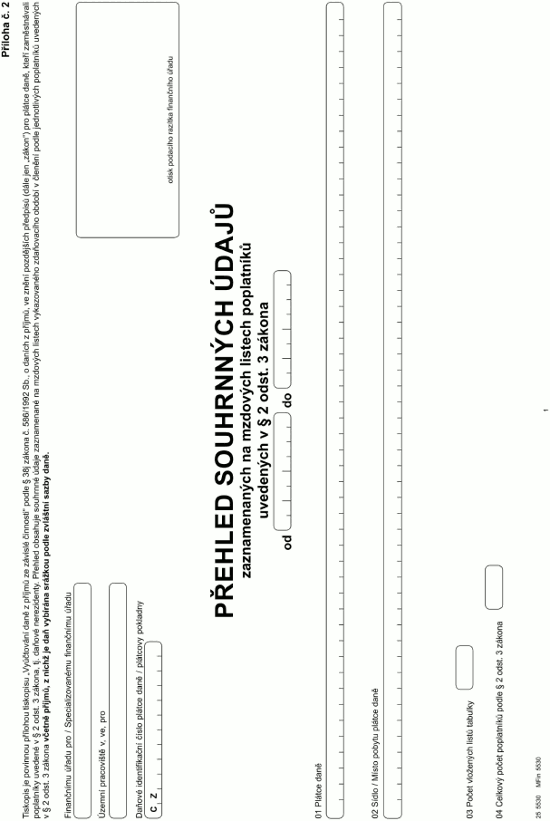
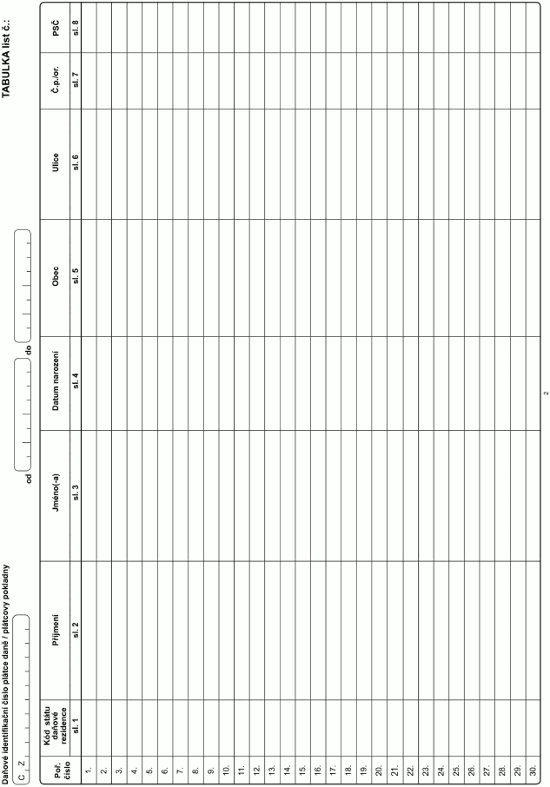
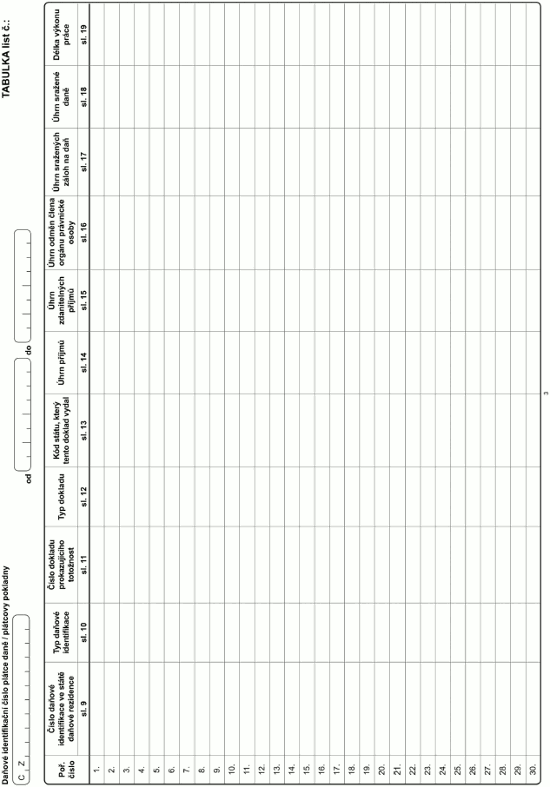
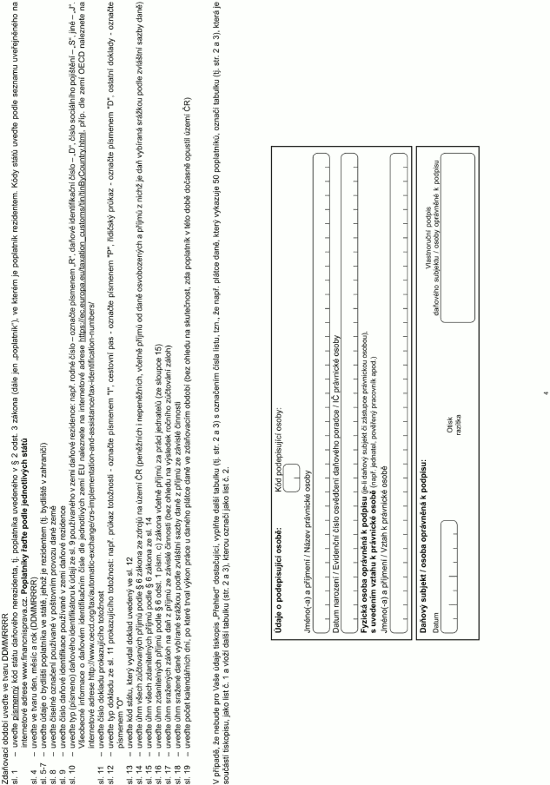
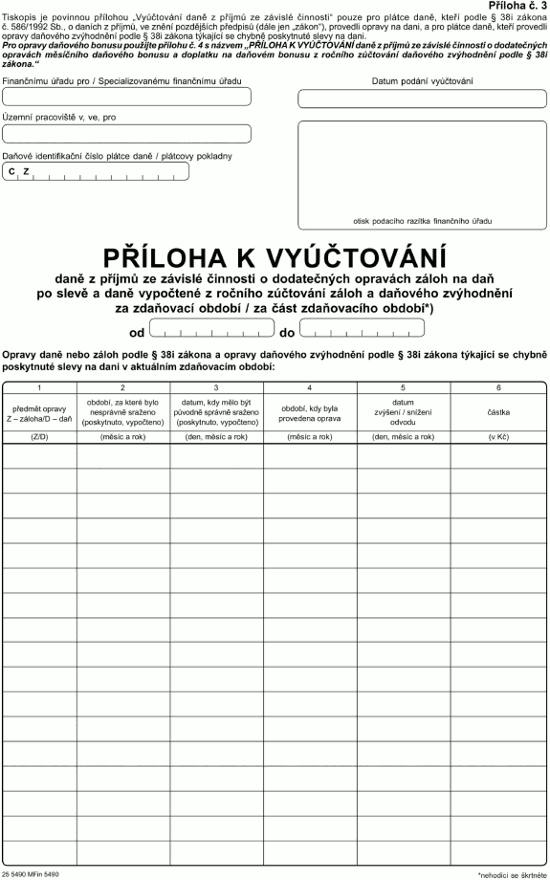
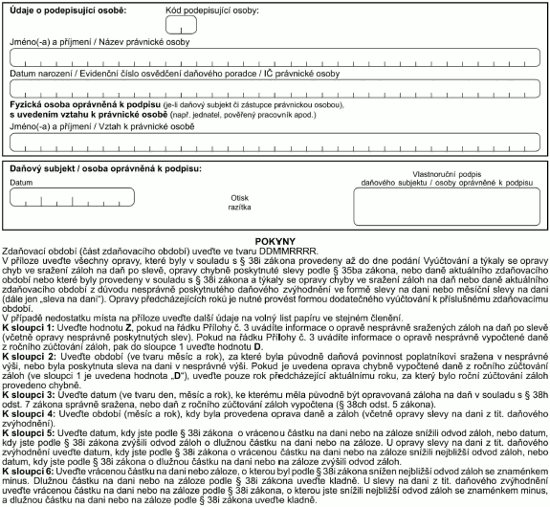
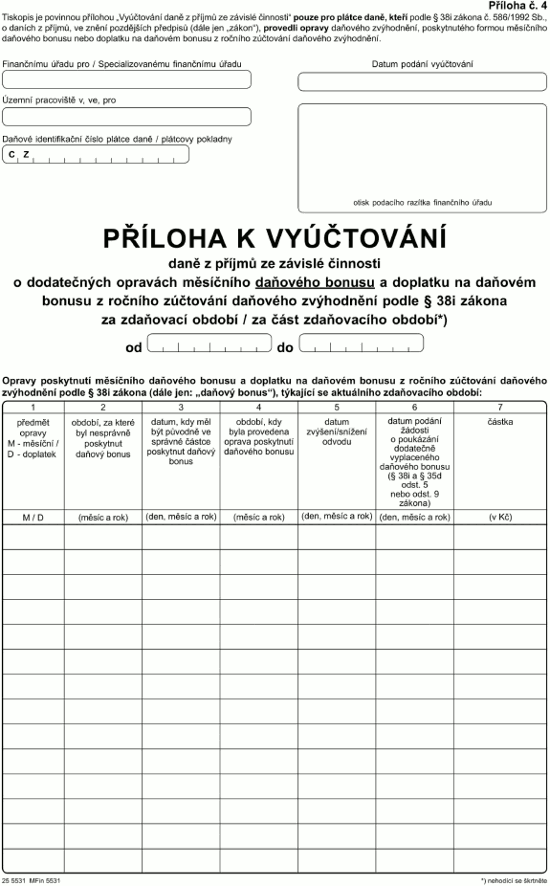
x) xxxxxxxxxx xxxx x xxxxxx xx závislé xxxxxxxx je uveden x příloze č. 3 x xxxx xxxxxxxx,
x) xxxxxxxxxx xxxx xxxxxxxx srážkou xxxxx xxxxxxxx xxxxx xxxx z xxxxxx xxxxxxxxx a právnických xxxx xx xxxxxx x příloze č. 4 x xxxx xxxxxxxx,
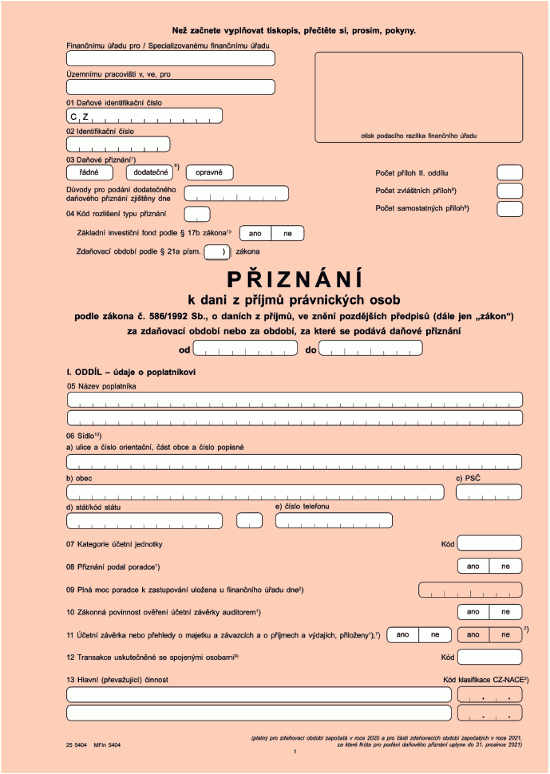
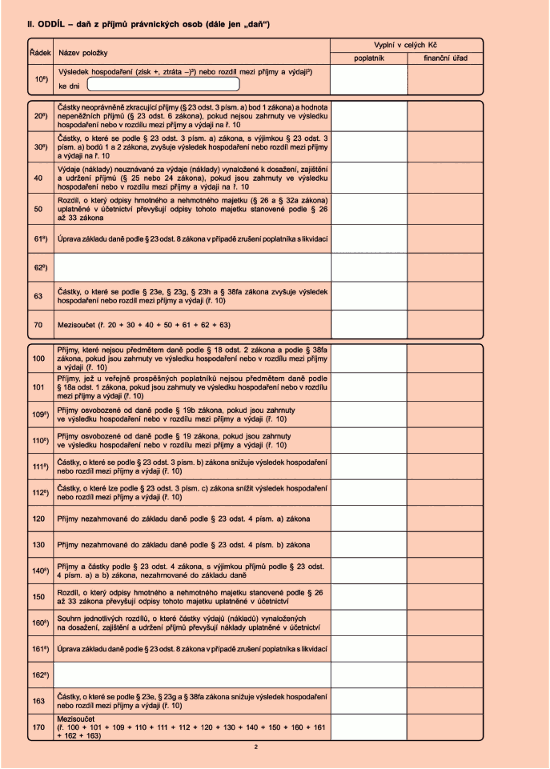
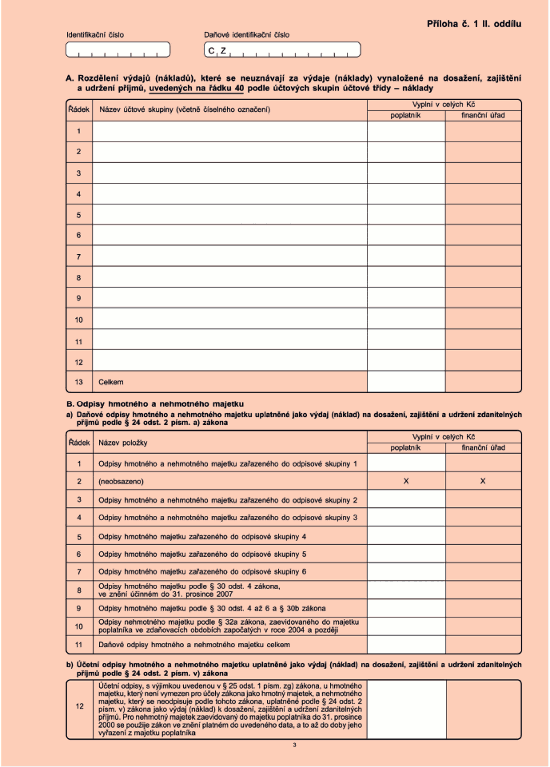
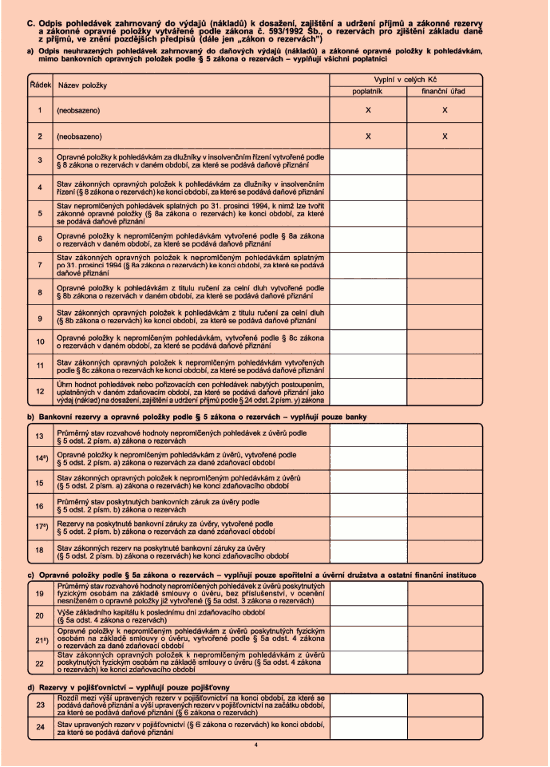
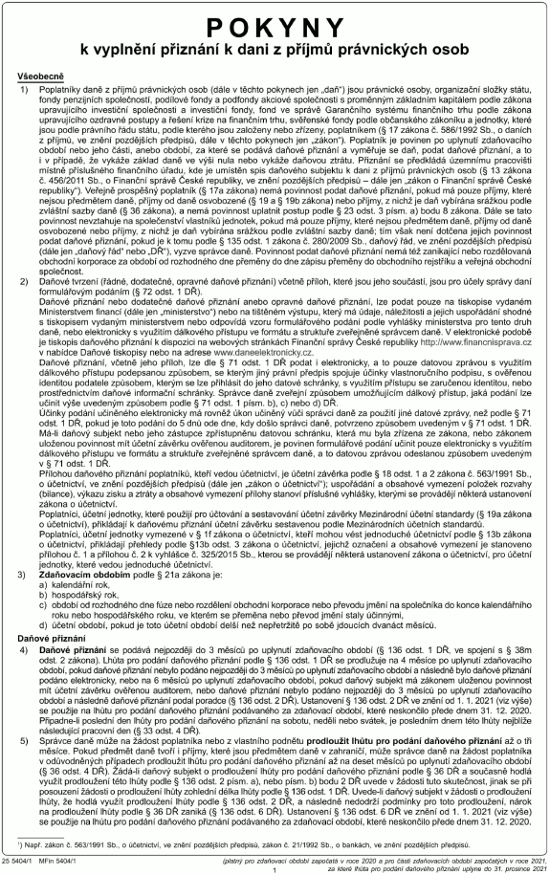
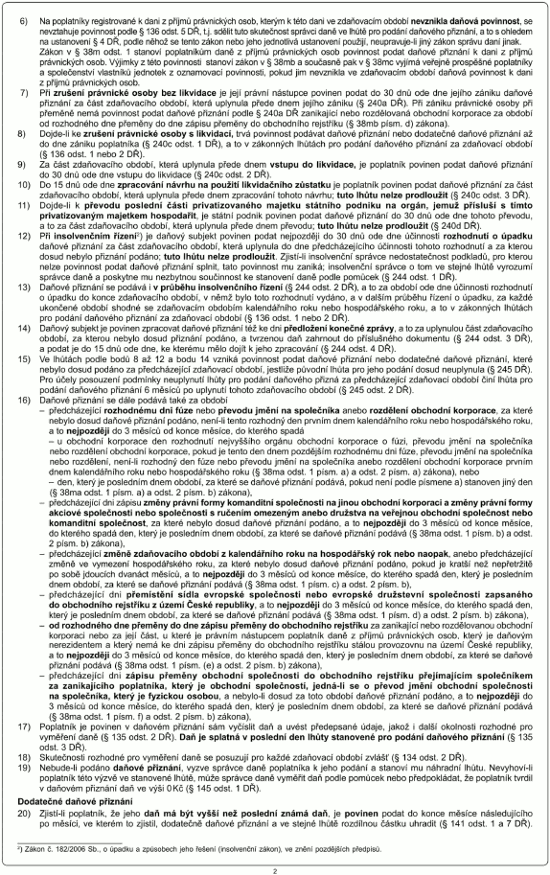
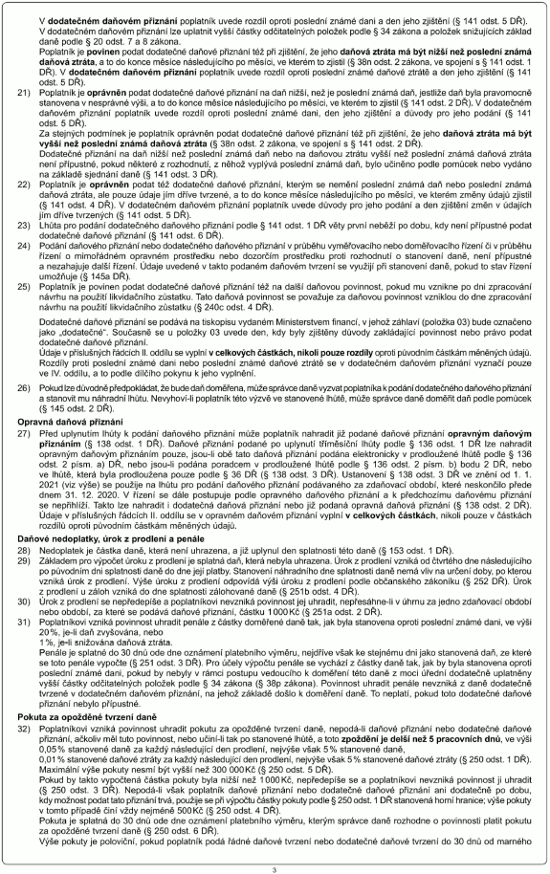
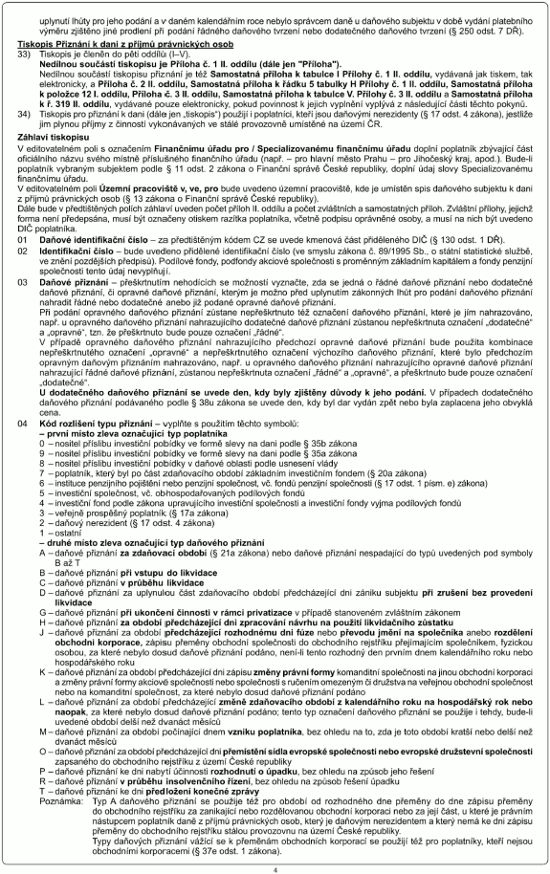
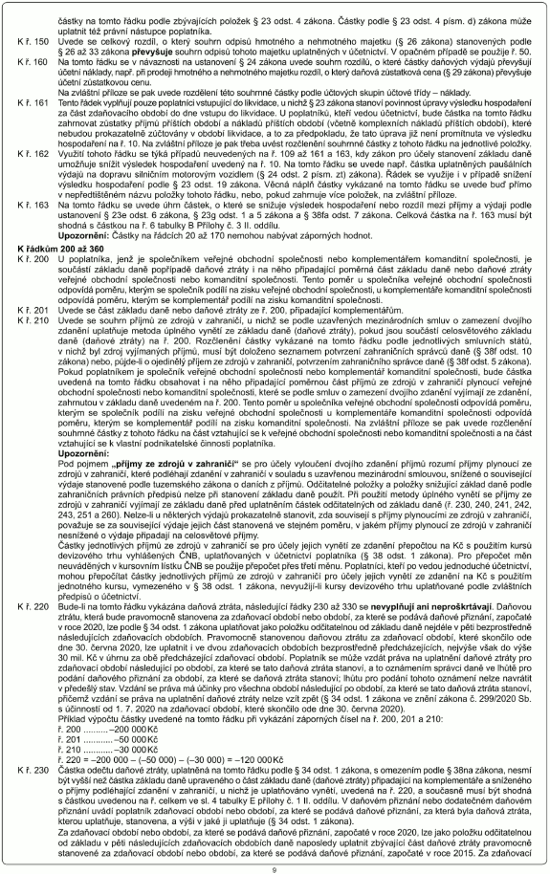
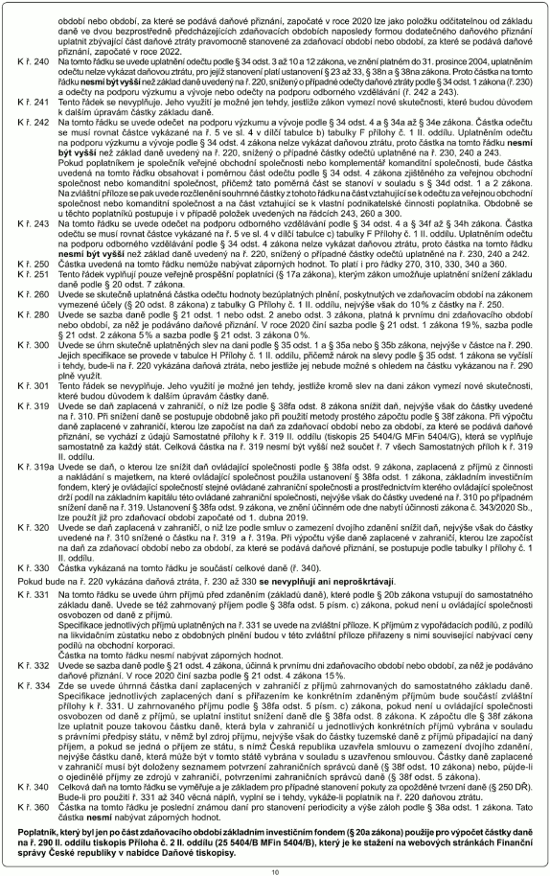
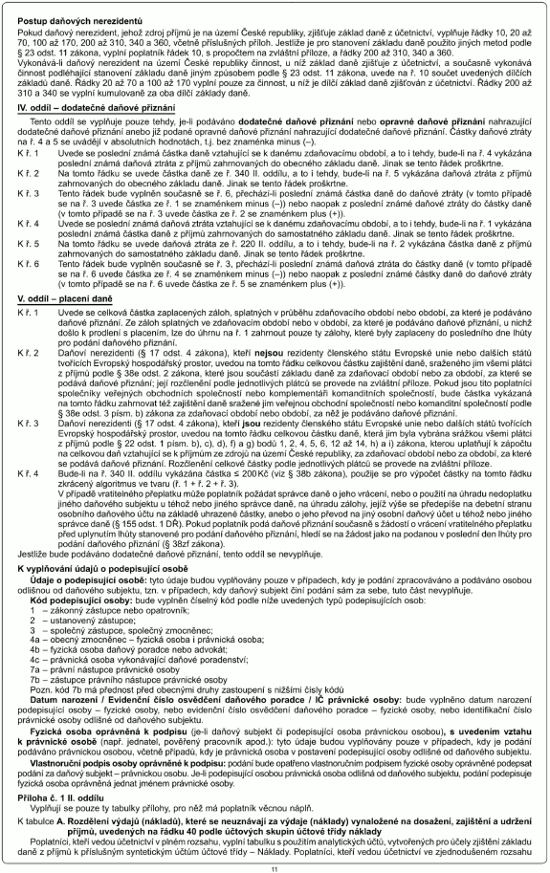
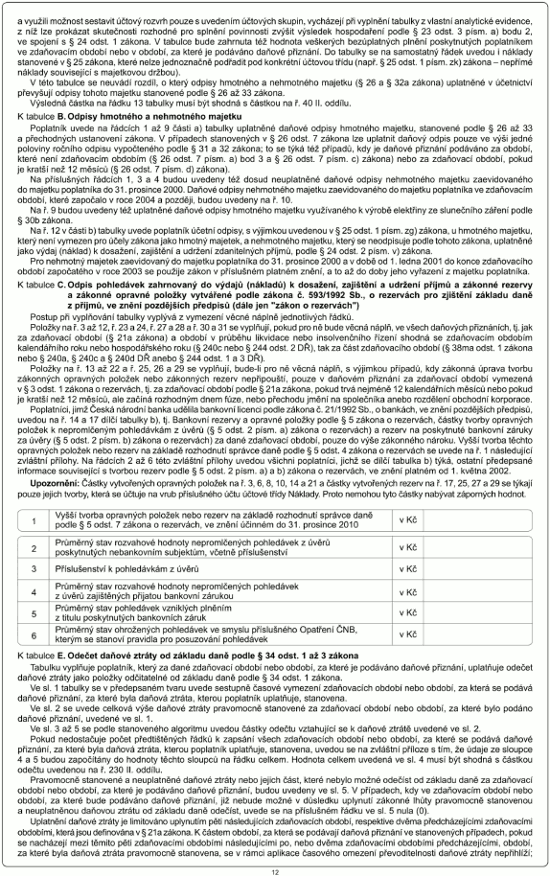
x) xxxxxxxx x xxxx x xxxxxx právnických xxxx xx uveden v příloze č. 5 k xxxx xxxxxxxx,
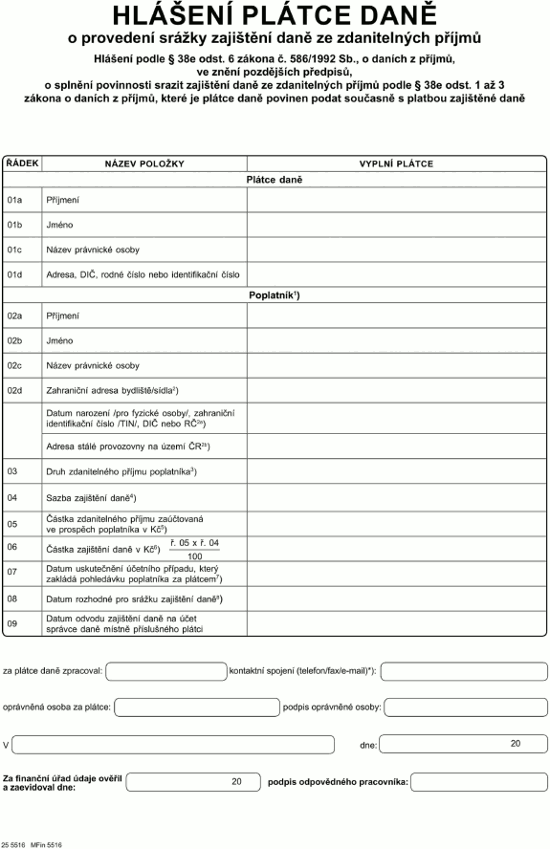
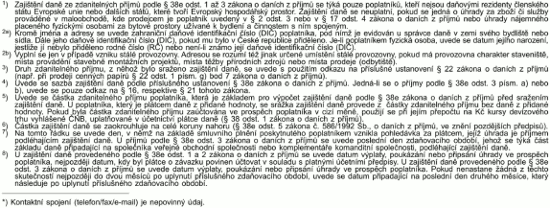
x) xxxxxxx xxxxxx xxxx x xxxxxxxxx xxxxxx xxxxxxxxx xxxx xx xxxxxxxxxxxx příjmů xx xxxxxx x příloze č. 6 x xxxx xxxxxxxx,
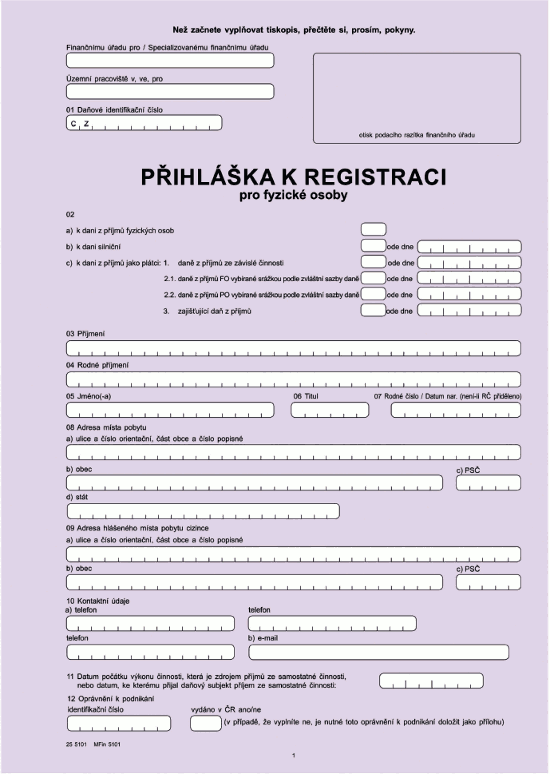
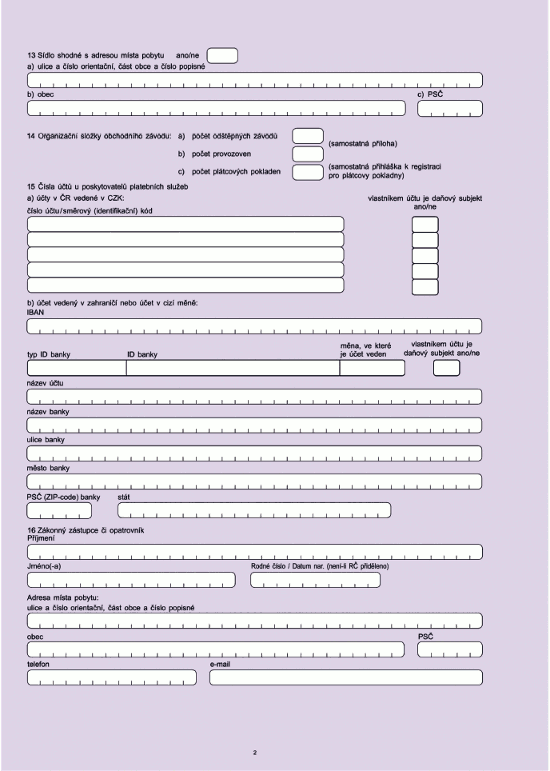
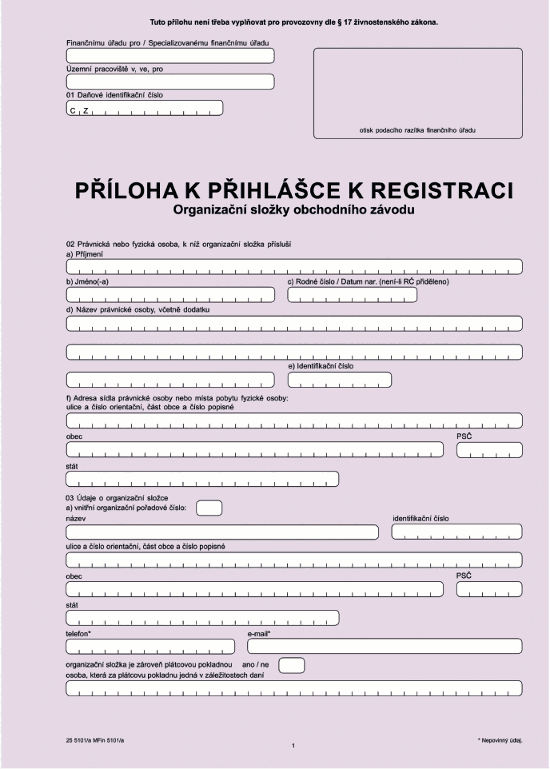
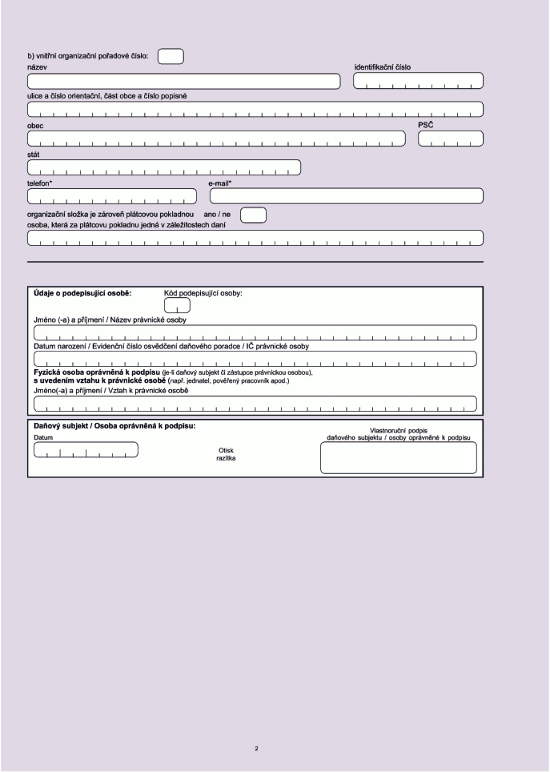
x) xxxxxxxxx x xxxxxxxxxx xxx xxxxxxx xxxxx xx xxxxxx x příloze č. 7 x xxxx vyhlášce,
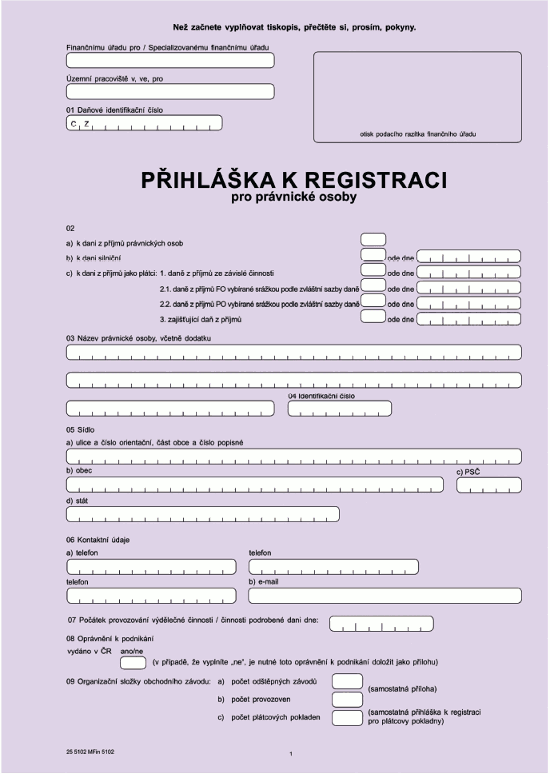
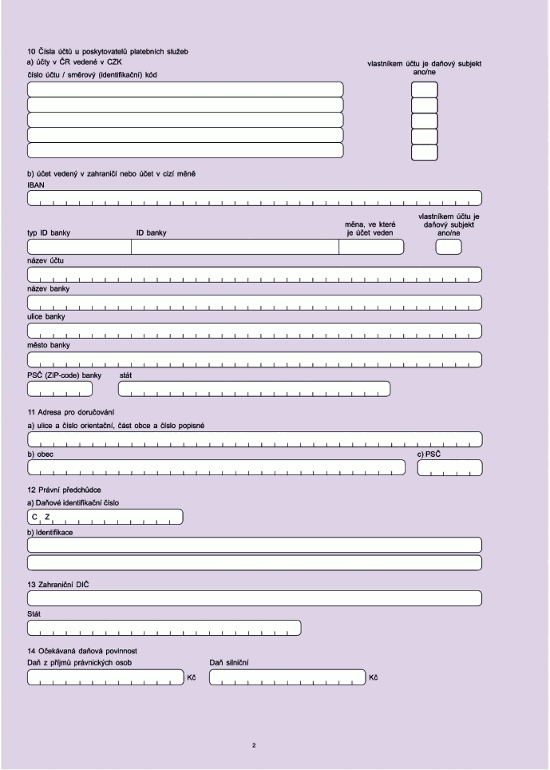
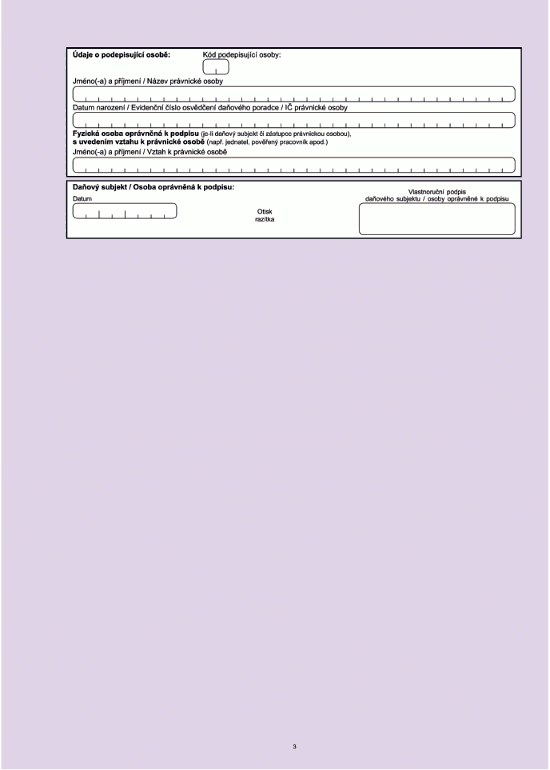
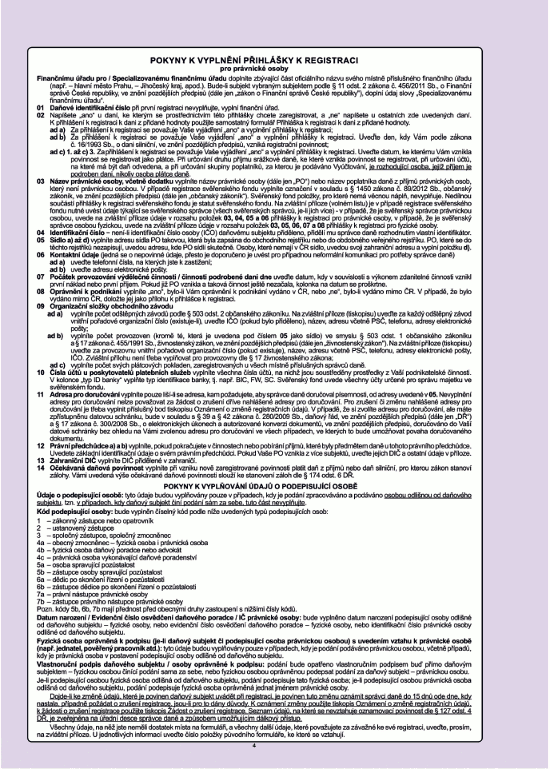
h) přihlášky x registraci pro xxxxxxxxx xxxxx xx xxxxxx x příloze č. 8 x této xxxxxxxx,
x) xxxxxxxxx x xxxxxxxxxx xxx xxxxxxxx pokladny xx uveden x příloze č. 9 k xxxx xxxxxxxx,
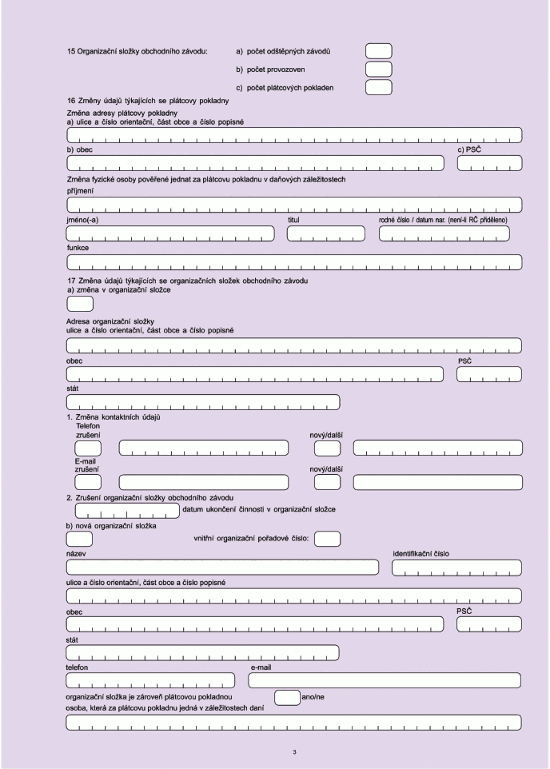
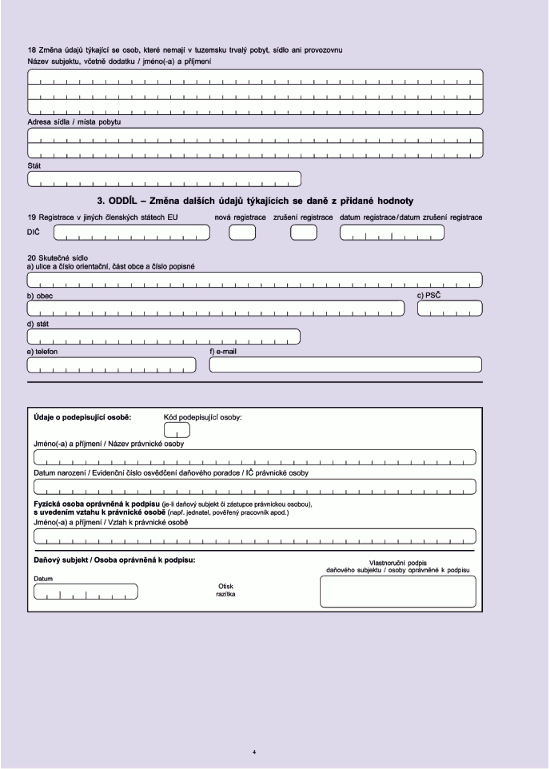
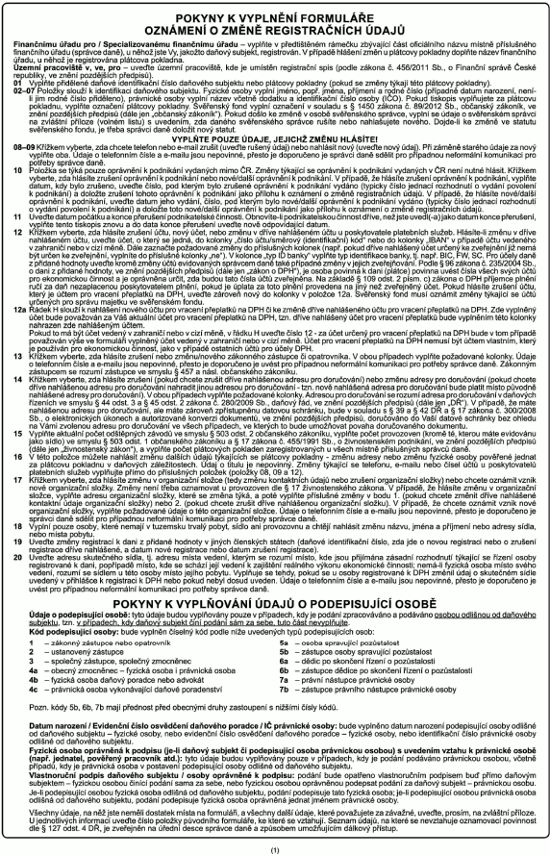
x) xxxxxxxx o xxxxx registračních údajů xx xxxxxx x příloze č. 10 x této xxxxxxxx,
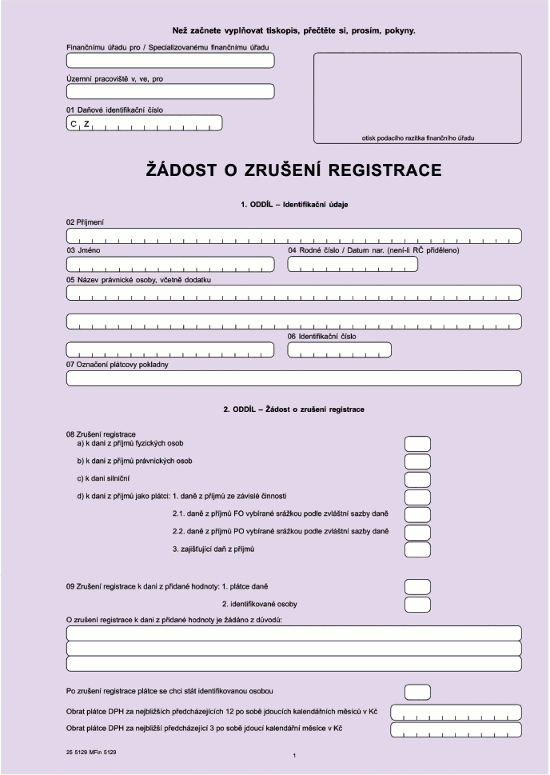
x) xxxxxxx x xxxxxxx xxxxxxxxxx je xxxxxx x příloze č. 11 x xxxx vyhlášce.
(2) Xxxxx xxxxx odstavce 1 xxxx xxxxxxx xxxxxx xxxxxxxxxx pokynů x jejich vyplnění.
§3
Xxxxxxxxxxx xxxxxx podané xxxxxxxxxxxx
Xxxxxxxxxxx xxxxxxxx xxxxxxxxxxx xxxxxx x údajů xxxxxxxxxxxx ve xxxxxxxxxxxx xxxxxx, xxxxx xxxx xxxxxxx xx vzoru xxxxx §2, xx xxxxxxx také x xxxxx xxxxxxxxx formulářového xxxxxx xxxxxxxxxx xxxxxxxx xxxx v případě, xx xx toto xxxxxx xxxxxxx elektronicky.
§5
Společná ustanovení
Tiskopis xxxxxxxxxxxxx xxxxxx xxxxxx Ministerstvem xxxxxxx, popřípadě xxxxxxxxx xxxxxxxxxxxxx xxxxxx zveřejněná xxxxxxxx xxxx, xx xxxxxxxx za xxxxxxxxxxxx xxxxx xxxxx §2, xxxxxxxxx xx xxxxxxxxxxxx xxxxxxxxxxxx xxxxxxxx xxxxxxxxxxx xxxxxx a xxxxx xxxxx §3 xxxx x xxxxxxx, že
a) xxxxxxx část je x jiném xxx xxxxxx jazyce,
b) xxxxxxxx xxxxxxx xxxx x xxxxxxx xxxxxx,
x) xxxxxxxx xxxxxxxx x části xxxxx, xxxxxx xxxxxxxxx xxxx požadavek na xxxxxxx xxxxxxx xxxxxxxxxxx xxxxx,
x) xx xx xxxxxx xxxxx v xxxxxxxxxx xxxxxxx odchyluje x důsledku xxxxxxxxx xxxxxxxxxxxxxxx postupů výroby xxxxxxxxx.
§6
Xxxxxxxxx xxxxxxxxxx
(1) Xxxxxxxx xxxxxxxxxxxxx xxxxxx xxx xxxx z xxxxxx xxxxxx Xxxxxxxxxxxxx xxxxxxx xxxxx dnem xxxxxx xxxxxxxxx této vyhlášky xx xxxxxxxx xx xxxxxx v xxxxxxx x touto xxxxxxxxx.
(2) Xxxxxxxxx xxxxxxxxxxxxx xxxxxx xxx xxxx x xxxxxx zveřejněná xxxxxxxx xxxx xxxxx xxxx xxxxxx xxxxxxxxx xxxx xxxxxxxx se považuje xx zveřejněnou x xxxxxxx x touto xxxxxxxxx.
(3) Odstavce 1 x 2 xx xxxxxxxxx x případě xxxxxxxxxxxxx xxxxxx xxxxxxxxxxxx xx x xxxxxxxxxx.
§7
Xxxxxxxx
Xxxx vyhláška nabývá xxxxxxxxx xxxx 1. xxxxx 2021.
Ministryně xxxxxxx:
XXXx. Xxxxxxxxxxx, Xx.X., x. x.
Xxxxxxx x. 1 x xxxxxxxx č. 525/2020 Xx.
Xxxxxxxx x xxxx z xxxxxx xxxxxxxxx osob pro xxxxxxxxxx xxxxxx xxxxx xxxxxx xx xxxxxxx xxxxxxxx xx zdrojů xx xxxxx Xxxxx xxxxxxxxx (xxxxxx xxxxxxxx xxxxxxxxxxx Xxxxx xxxxxxxxx)


Příloha x. 2 x vyhlášce x. 525/2020 Xx.
Xxxxxxxx x xxxx z příjmů xxxxxxxxx xxxx


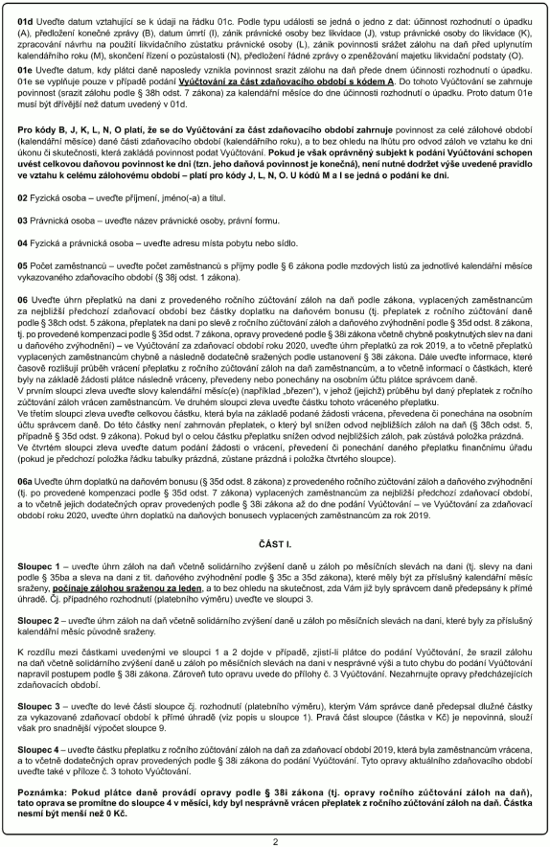
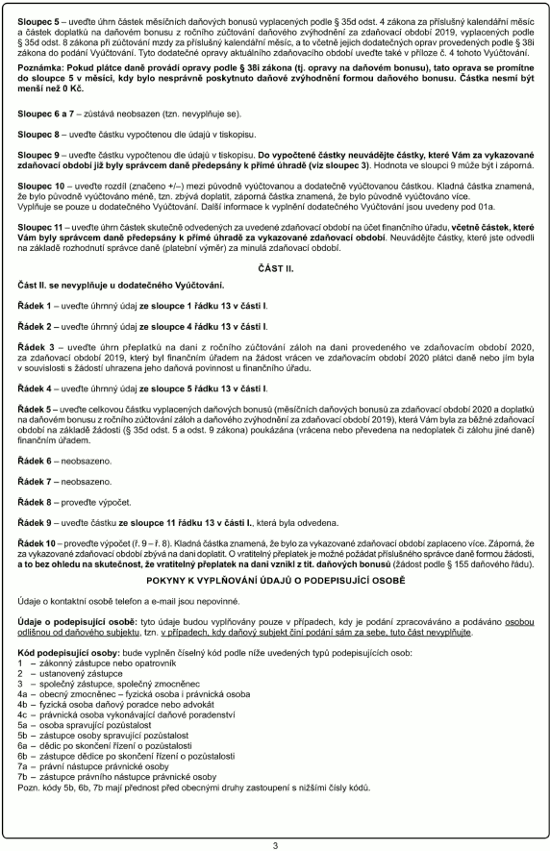
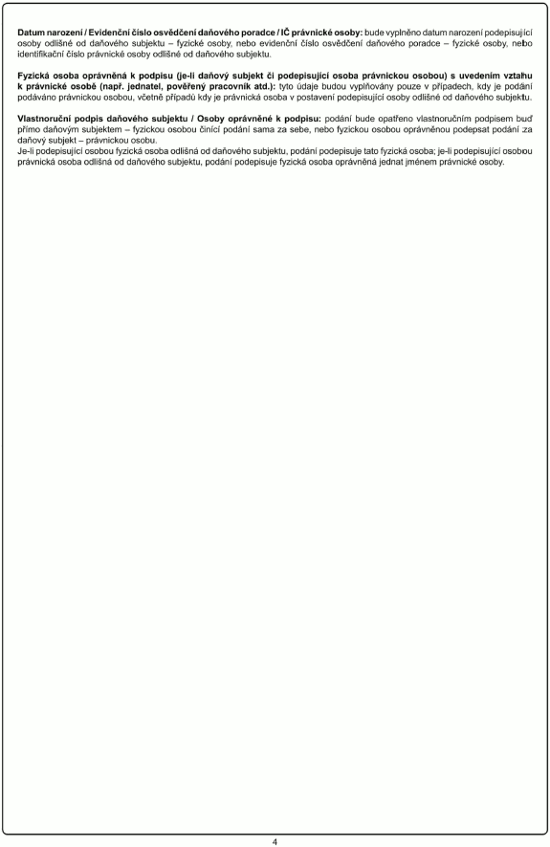
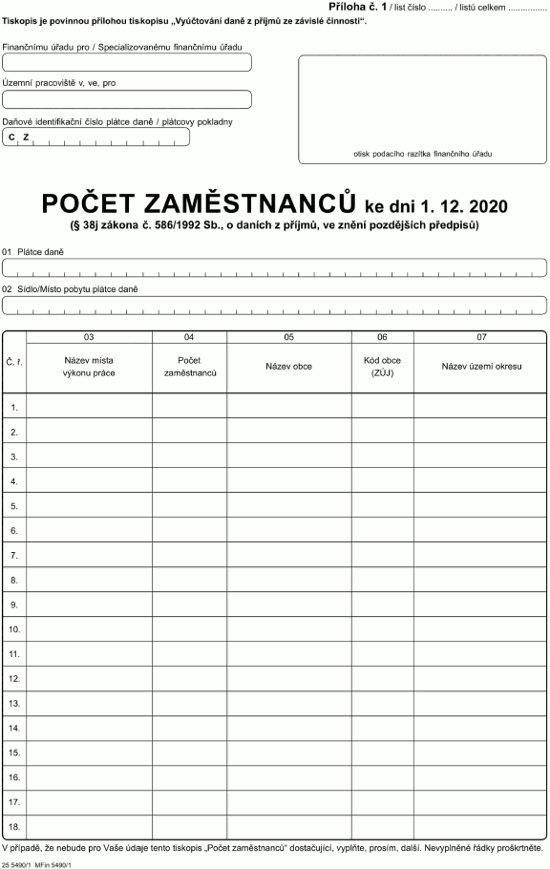
Xxxxxxx č. 3 x vyhlášce x. 525/2020 Xx.
Xxxxxxxxxx daně x příjmů xx xxxxxxx xxxxxxxx
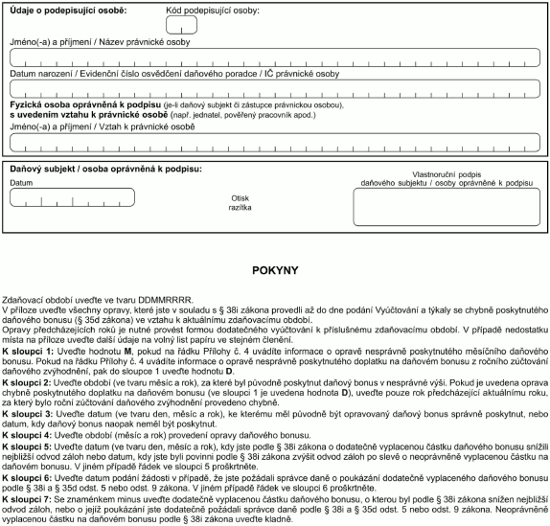
Xxxxxxx č. 4 x xxxxxxxx x. 525/2020 Sb.
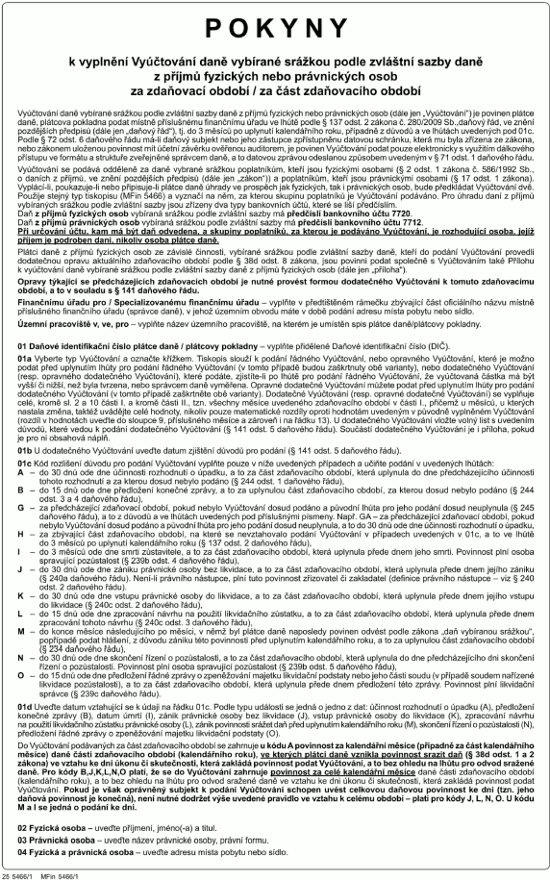
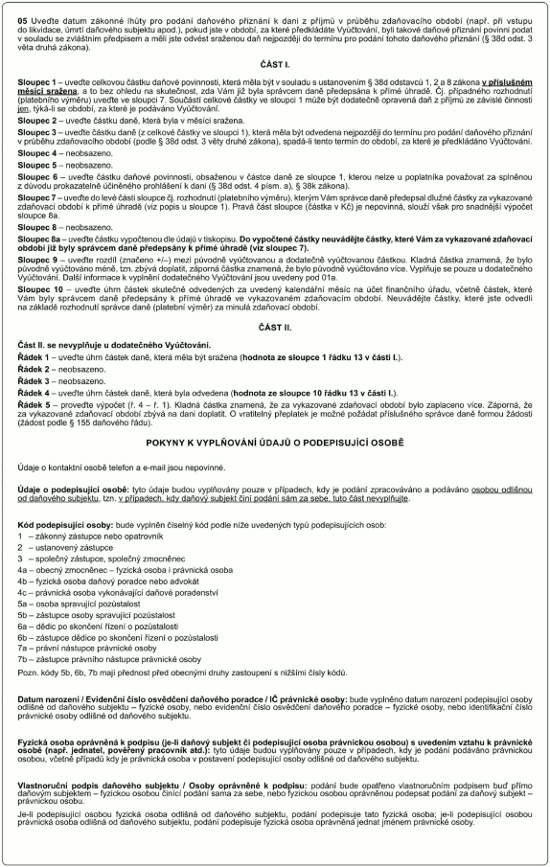
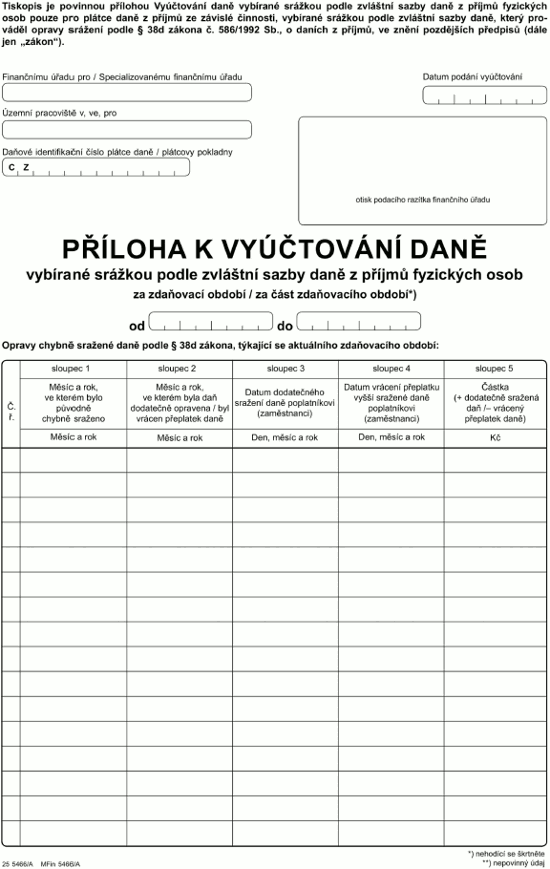
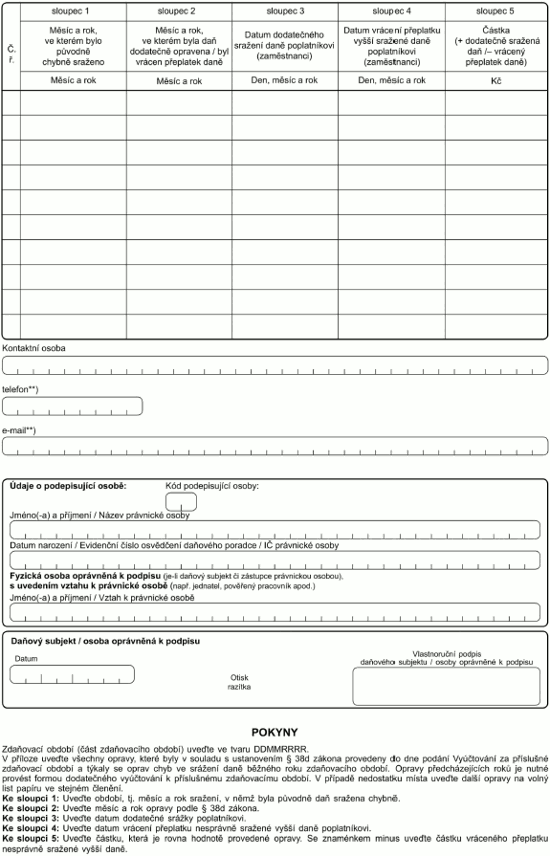
Vyúčtování daně xxxxxxxx xxxxxxx podle xxxxxxxx sazby daně x příjmů xxxxxxxxx / právnických osob
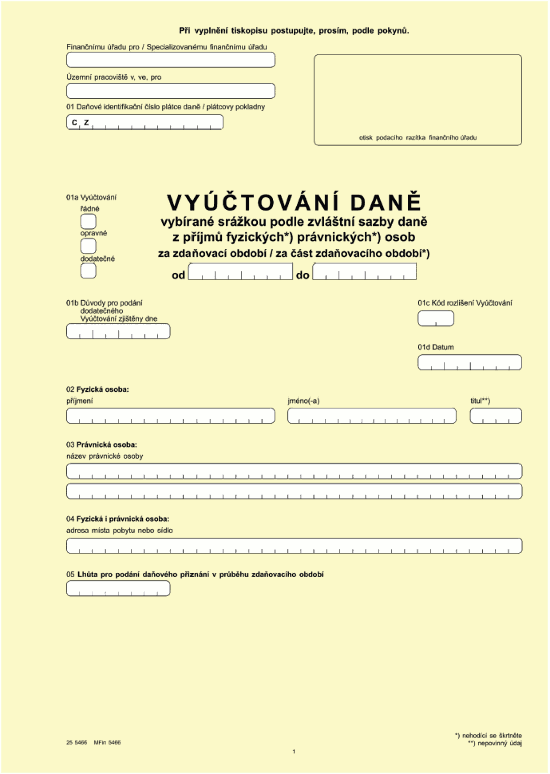
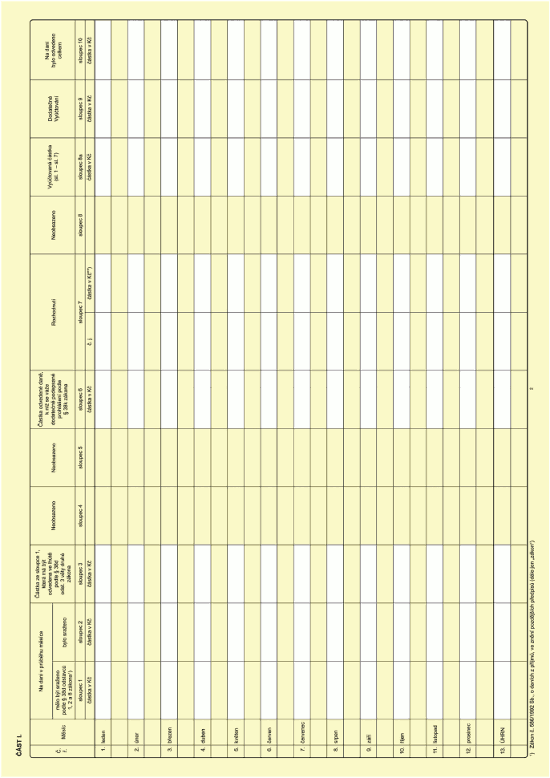
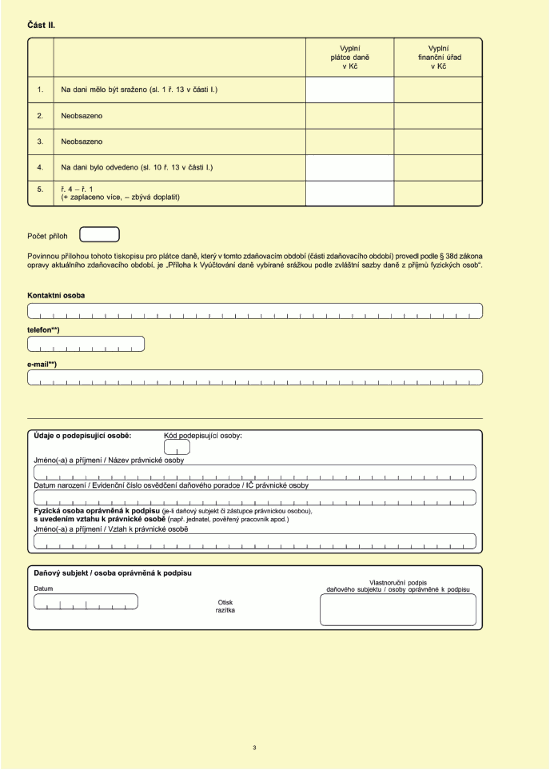
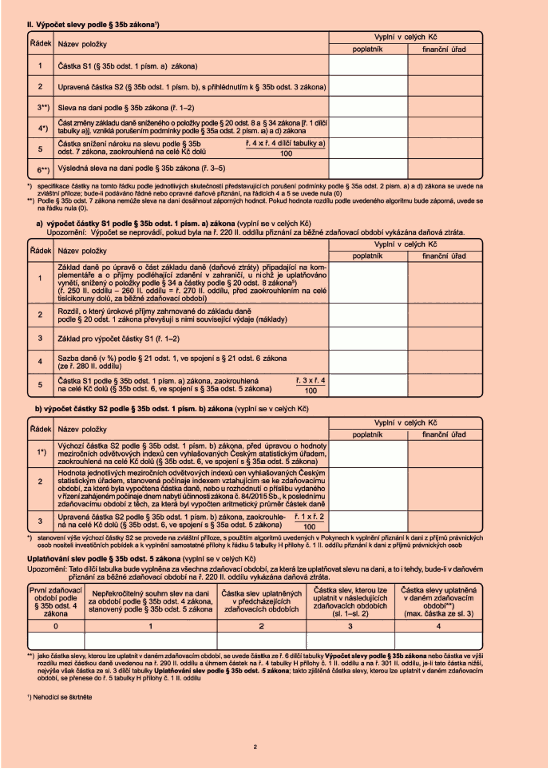
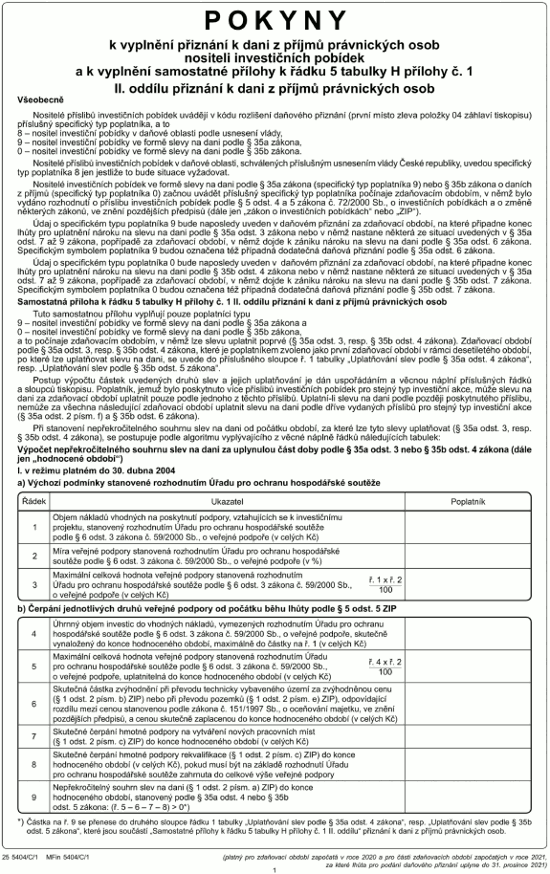
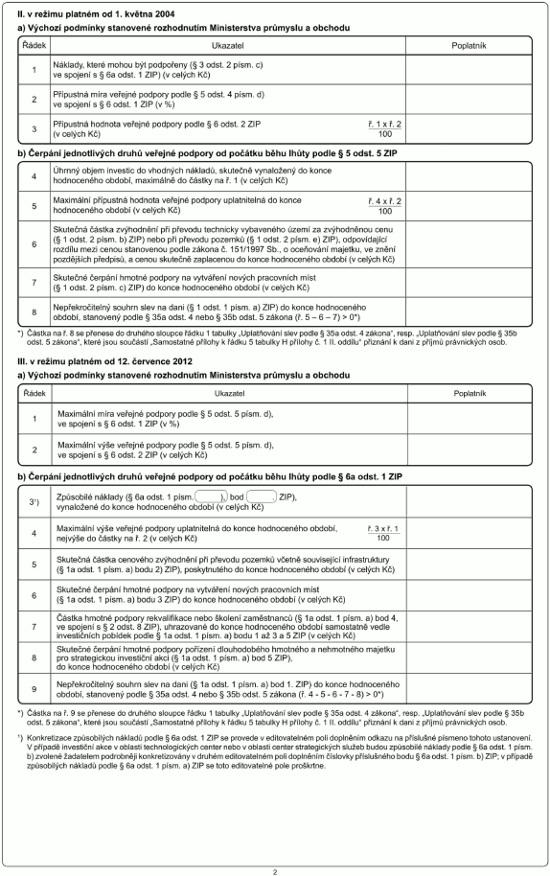
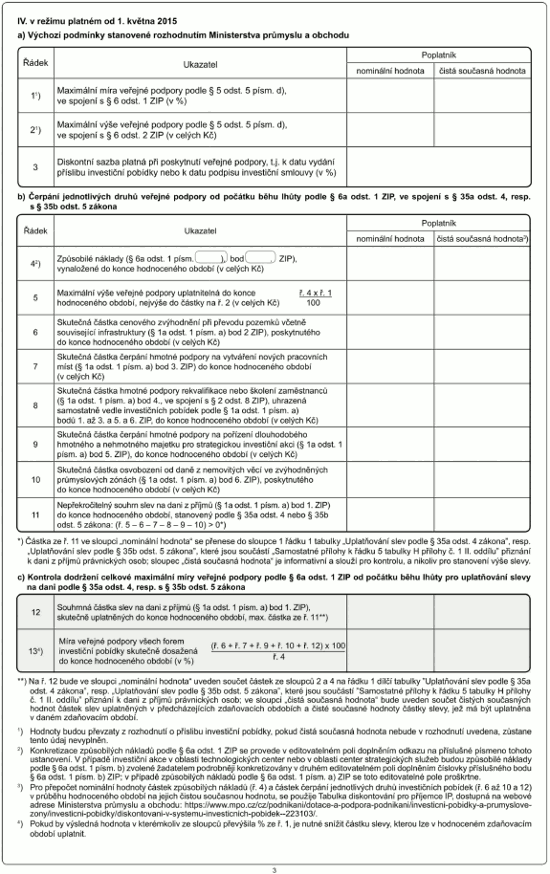
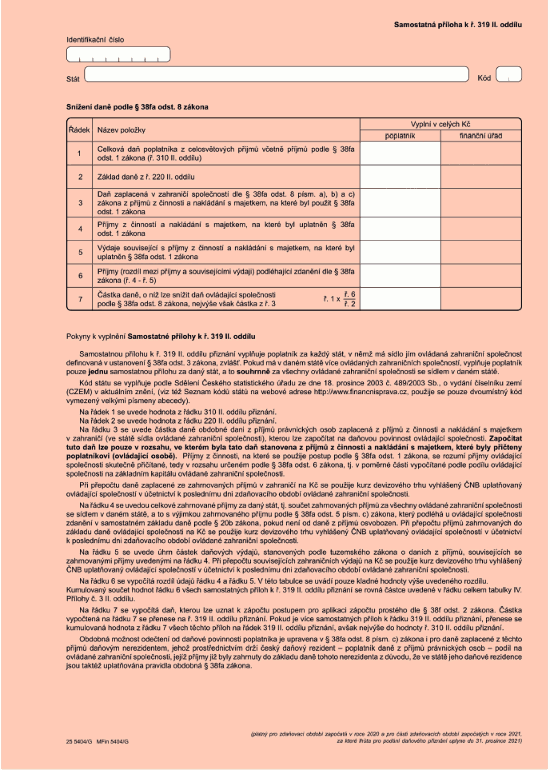
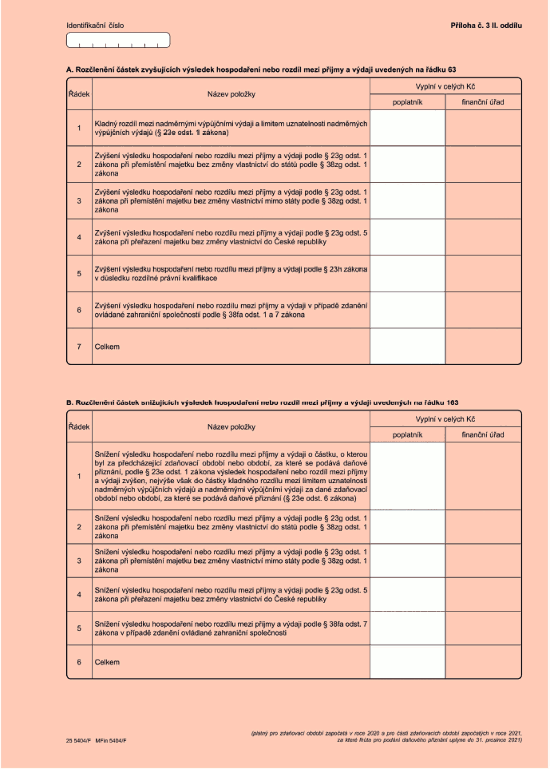
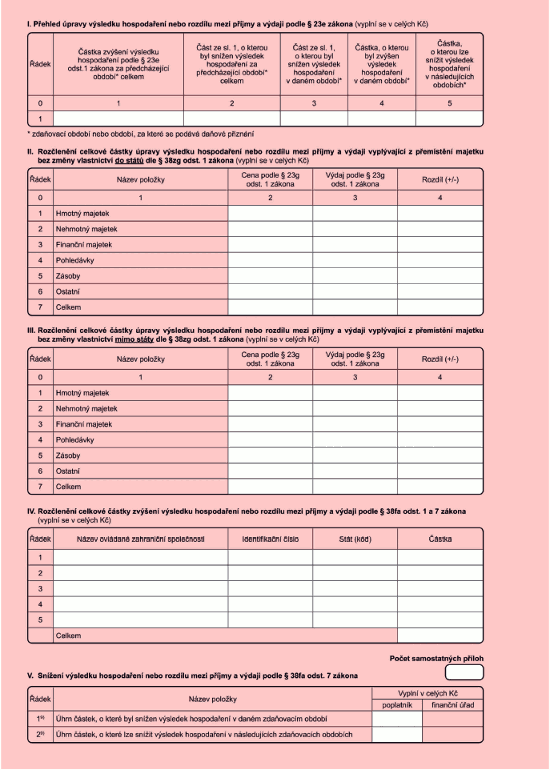
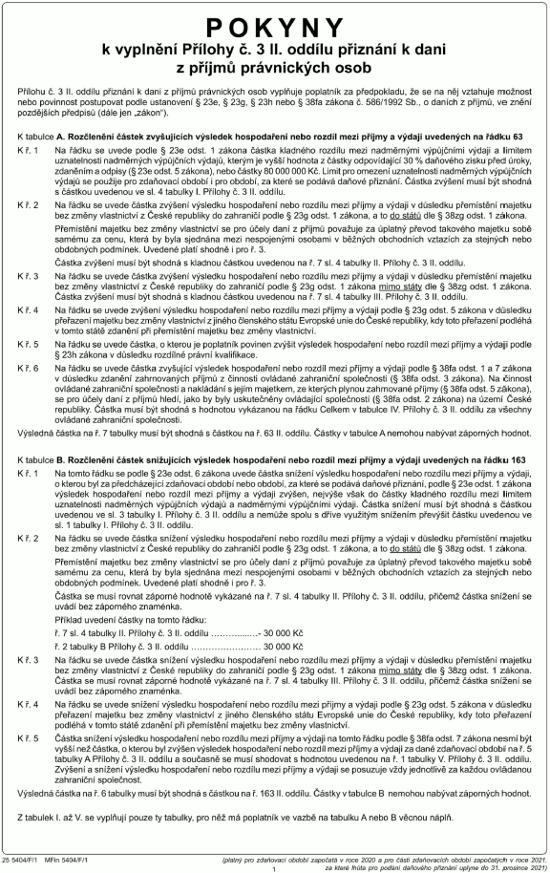
Xxxxxxx x. 5 x vyhlášce č. 525/2020 Xx.
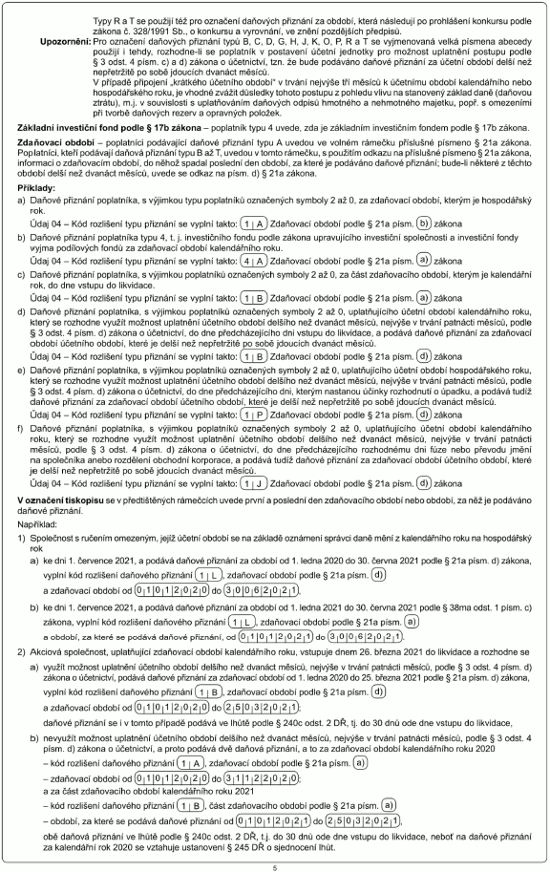
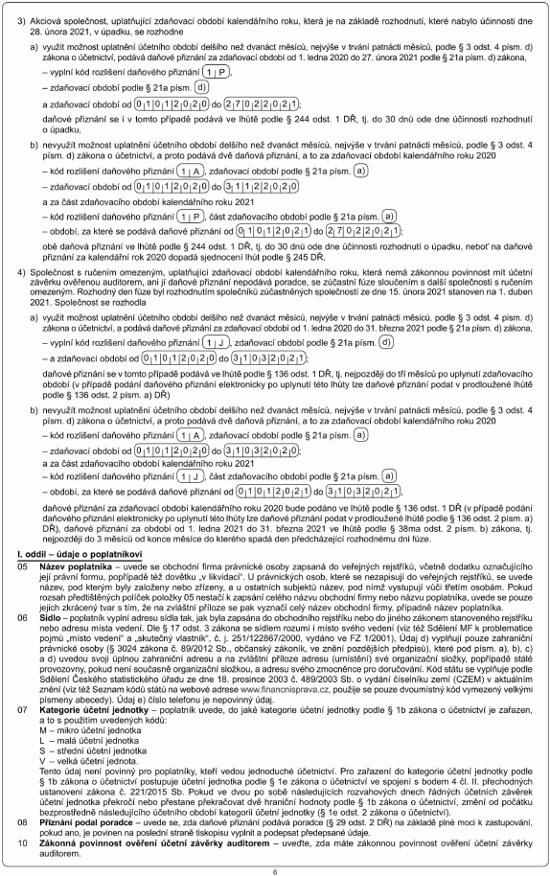
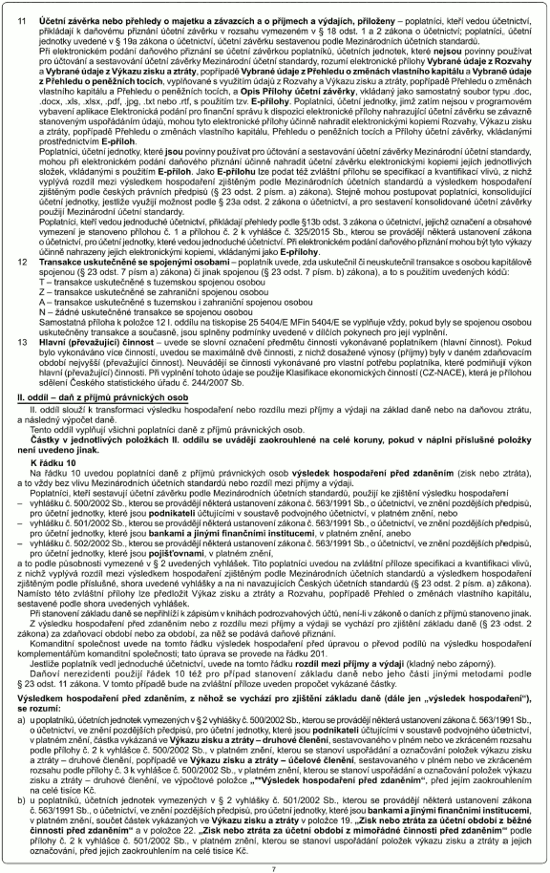
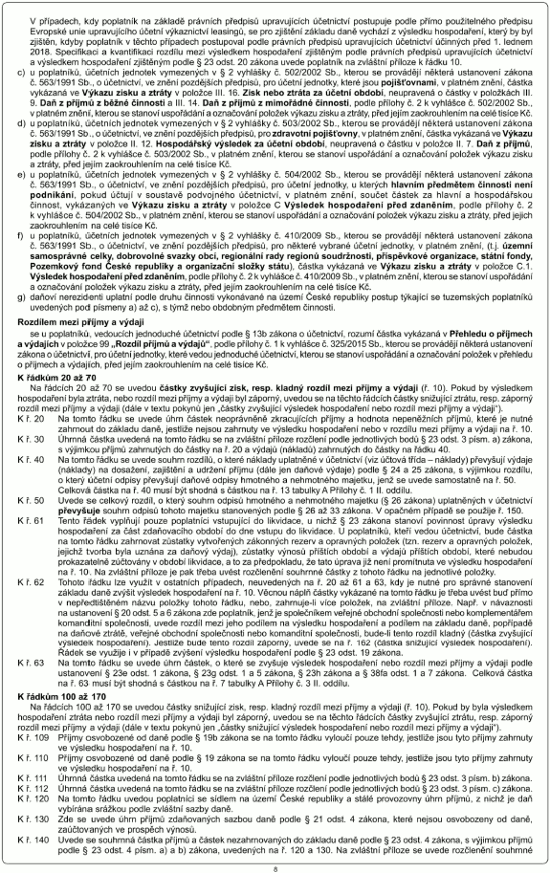
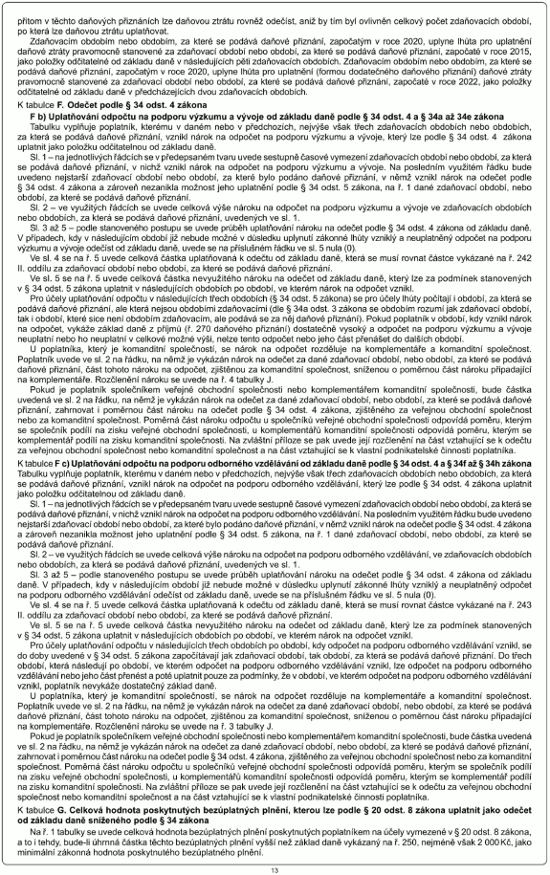
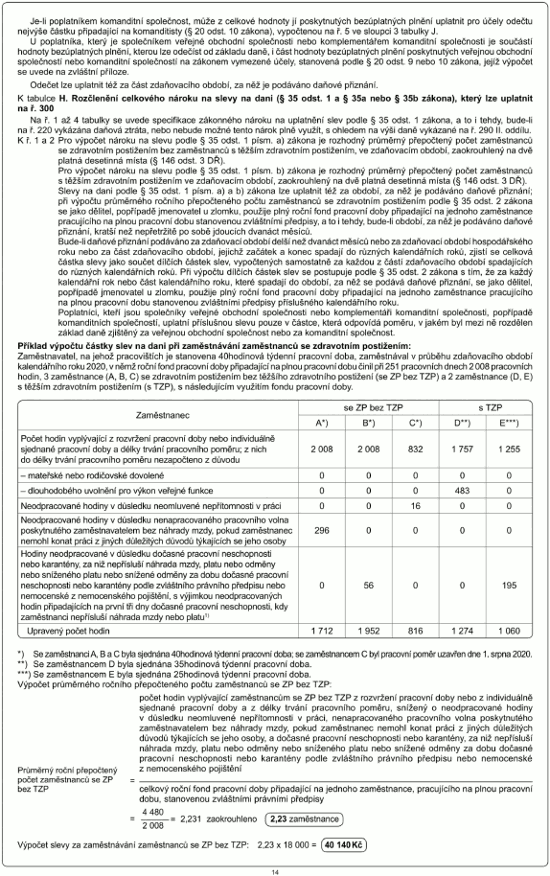
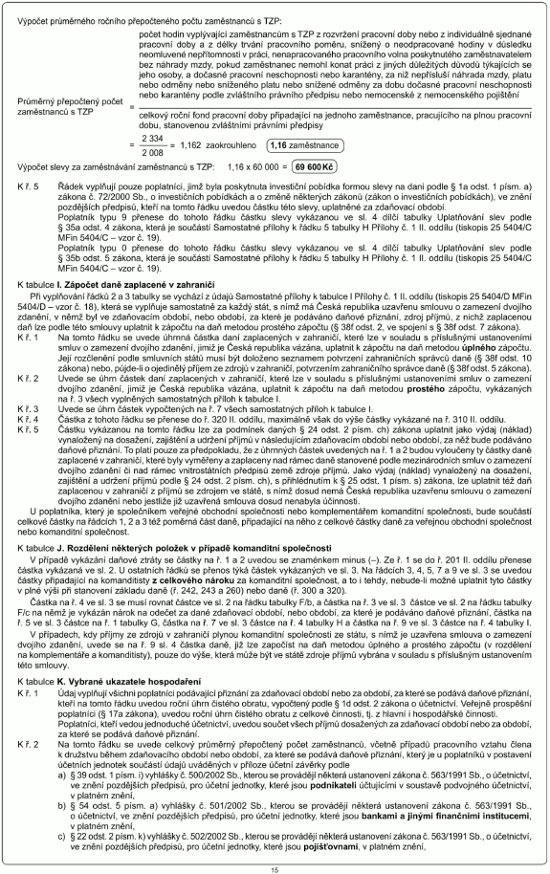
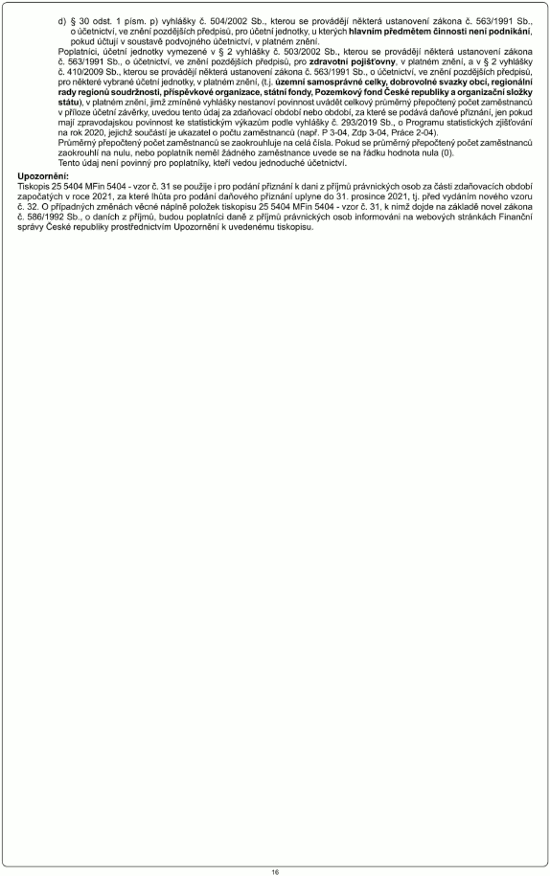
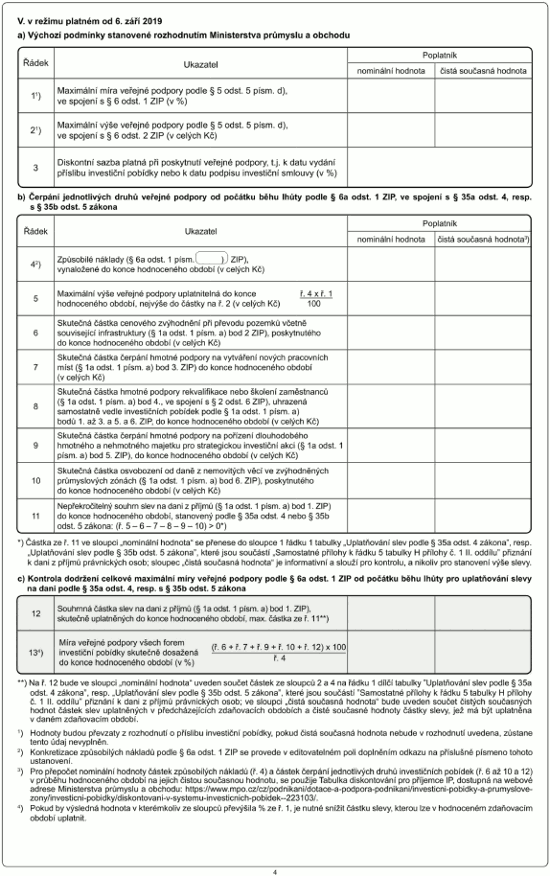
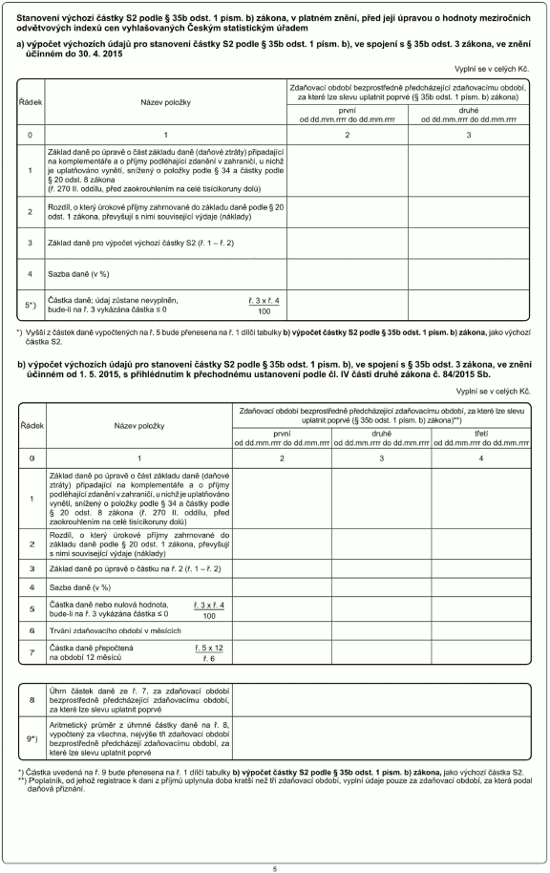
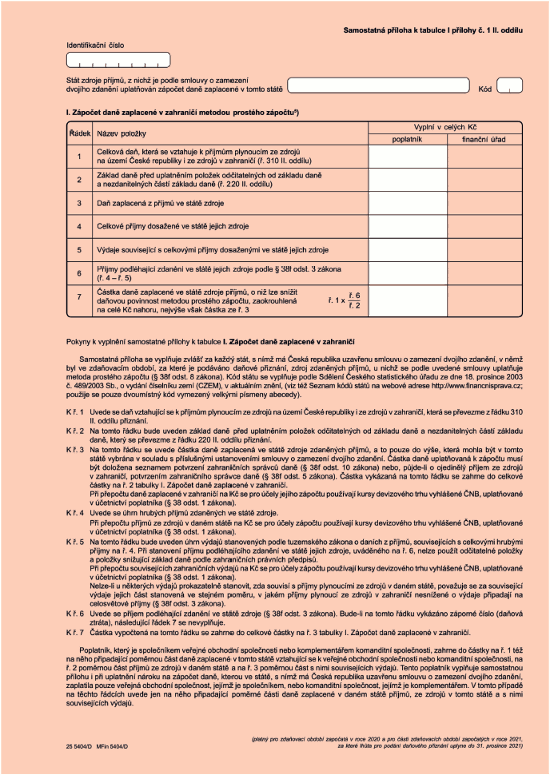
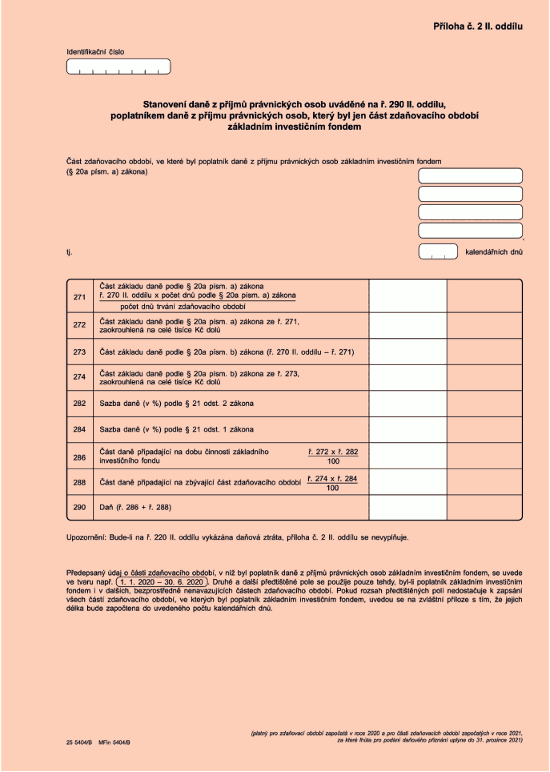
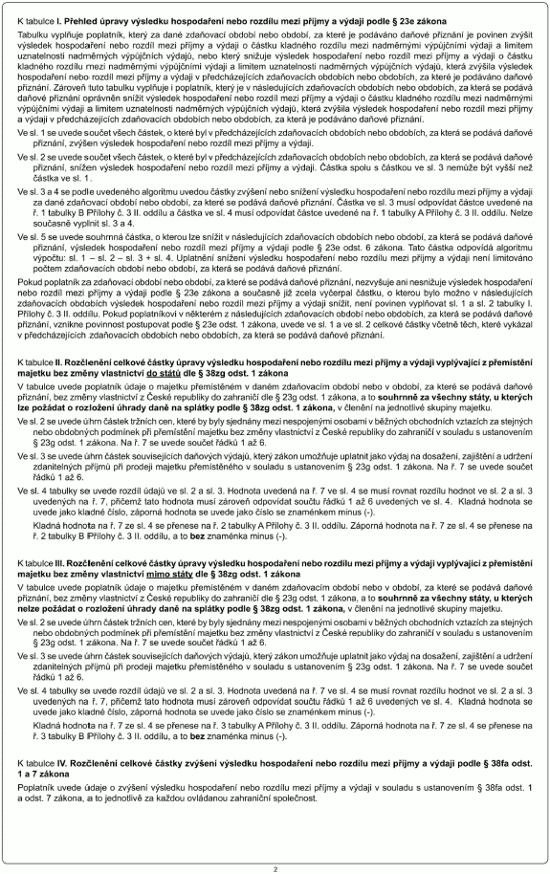
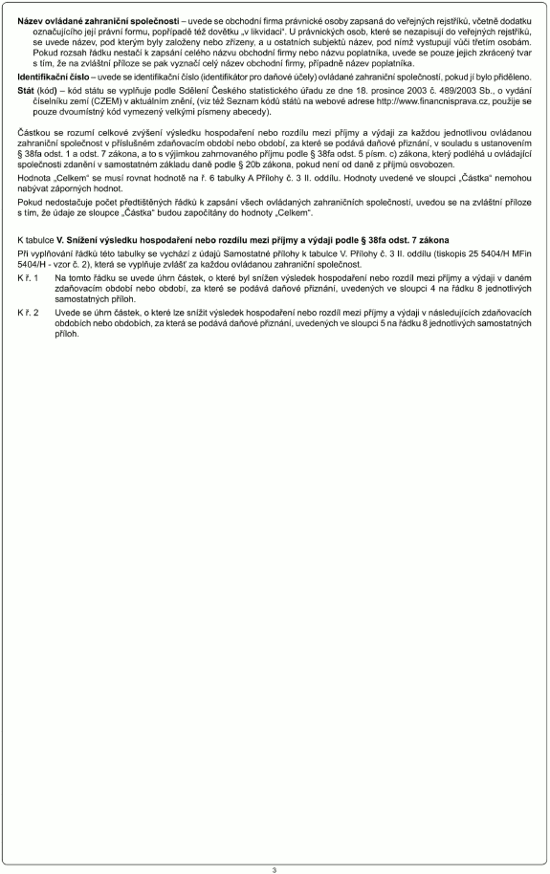
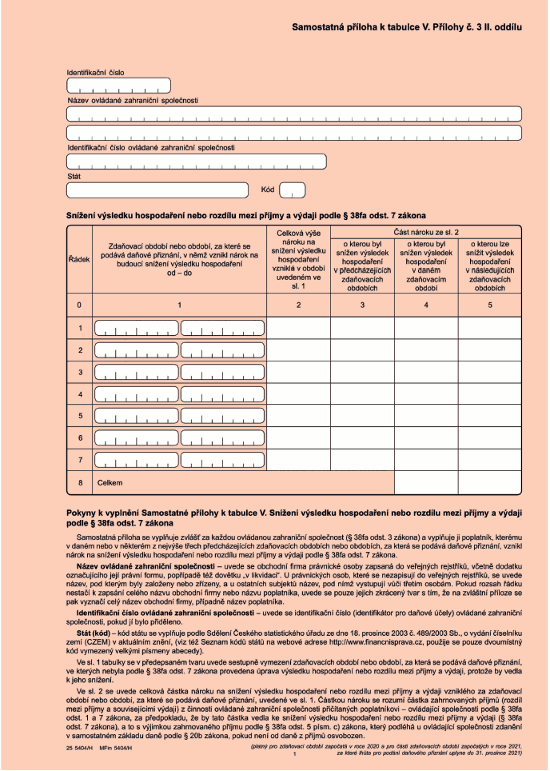
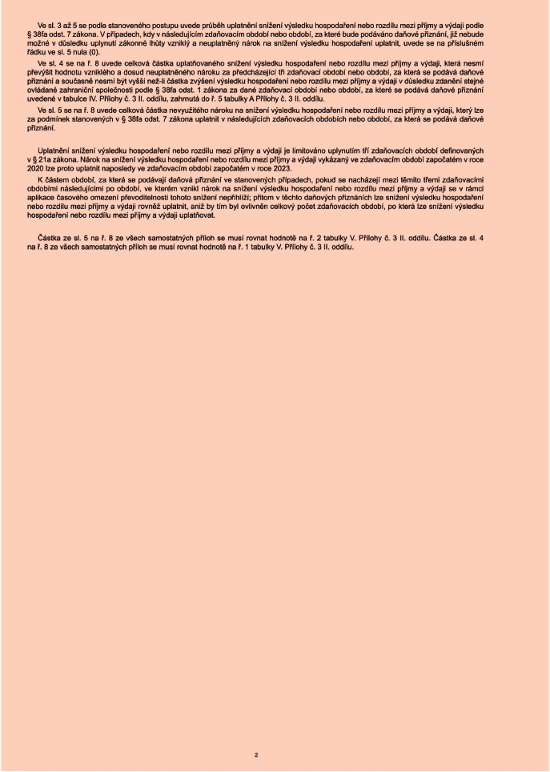
Xxxxxxxx x xxxx x xxxxxx xxxxxxxxxxx xxxx
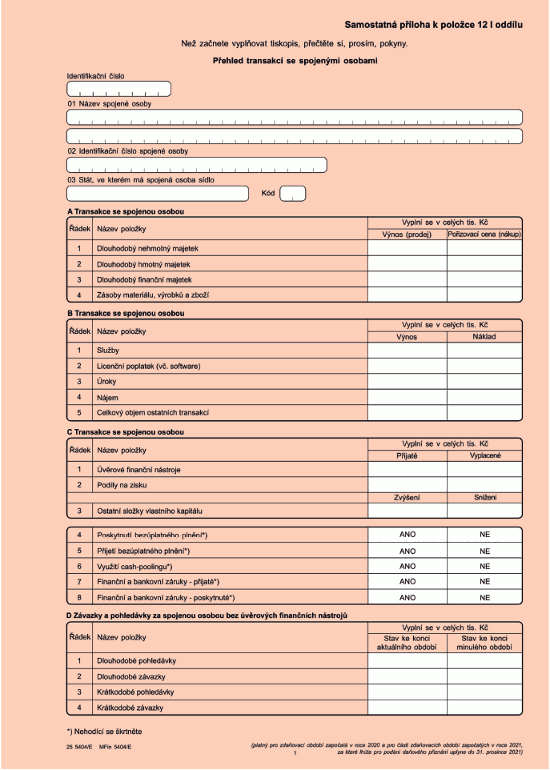
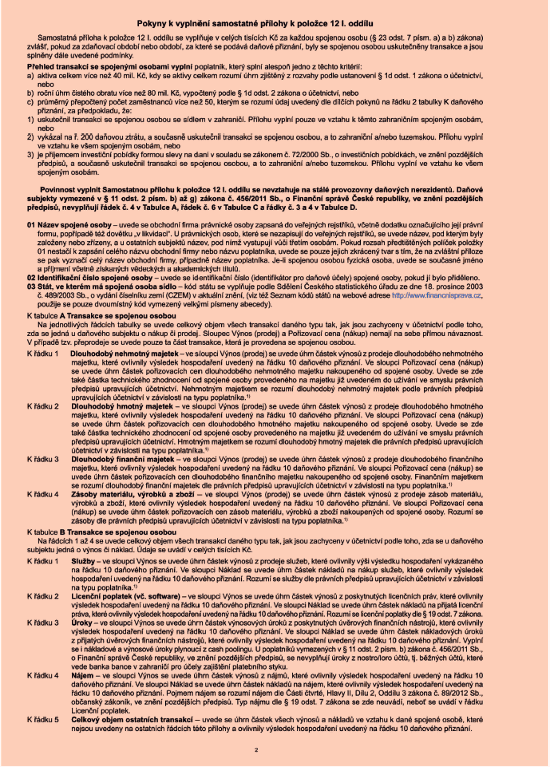
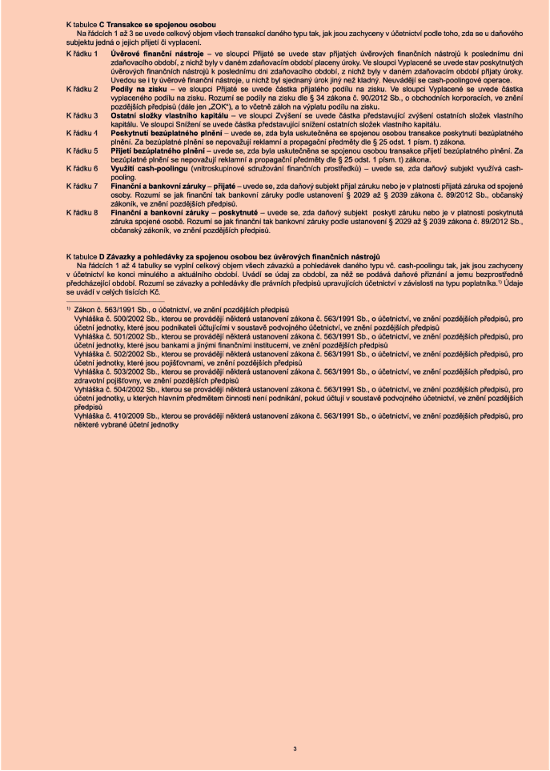
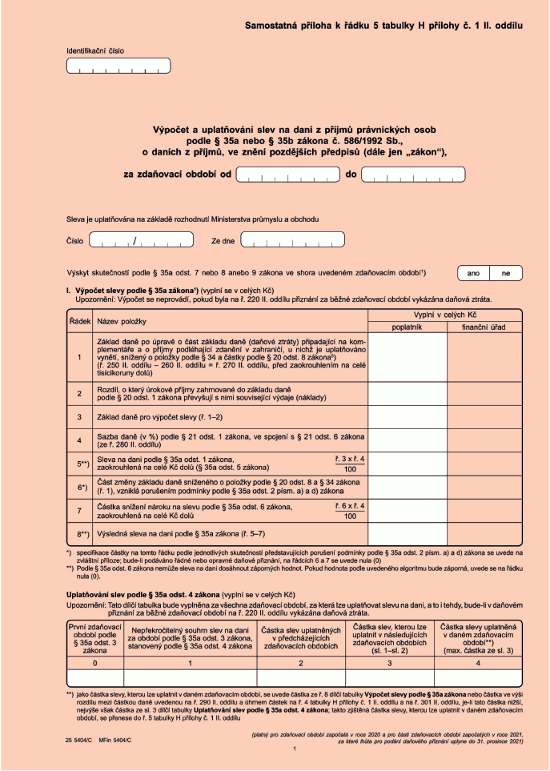
Xxxxxxx x. 6 x xxxxxxxx x. 525/2020 Xx.
Xxxxxxx xxxxxx xxxx x xxxxxxxxx xxxxxx xx xxxxxxxxx xxxx xx xxxxxxxxxxxx xxxxxx
Xxxxxxx x. 7 x xxxxxxxx x. 525/2020 Xx.
Xxxxxxxxx x xxxxxxxxxx xxx xxxxxxx xxxxx
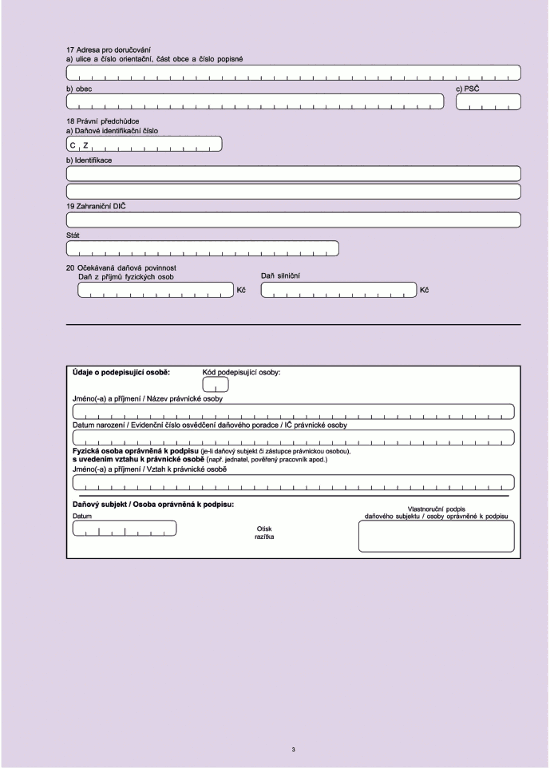
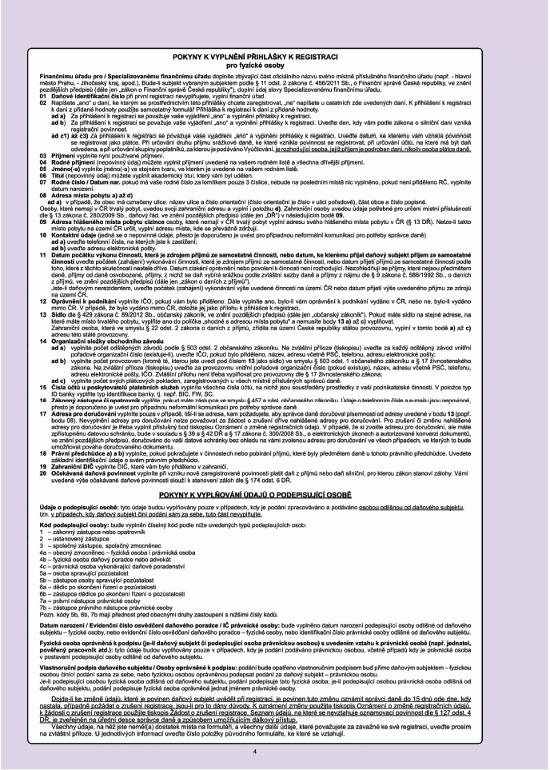
Příloha x. 8 x vyhlášce x. 525/2020 Sb.
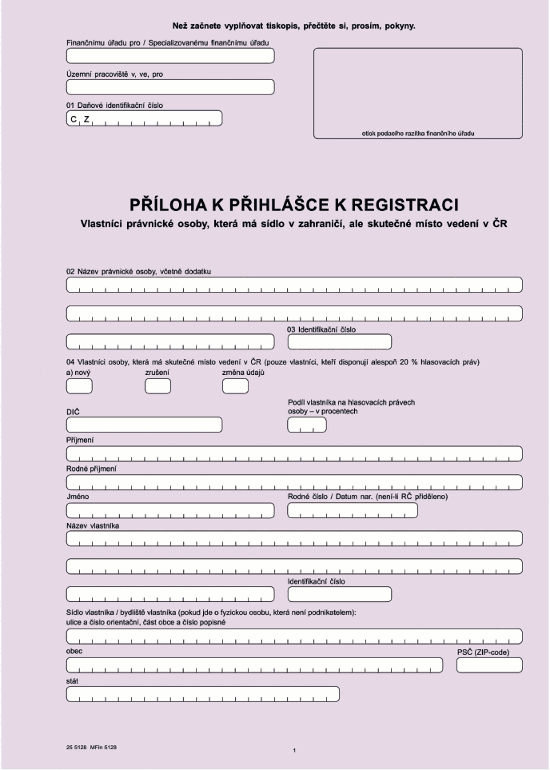
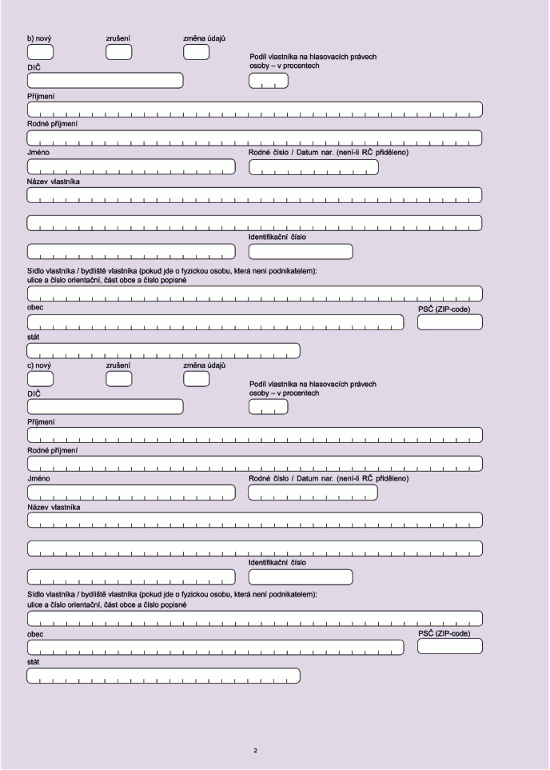
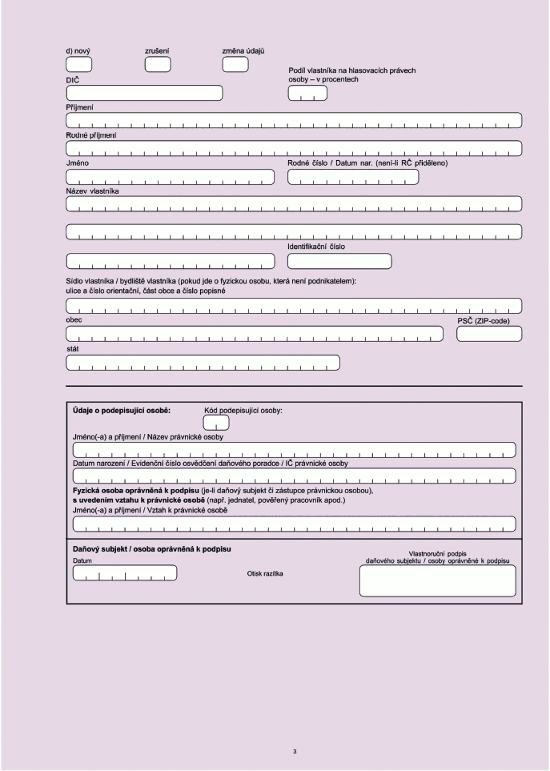
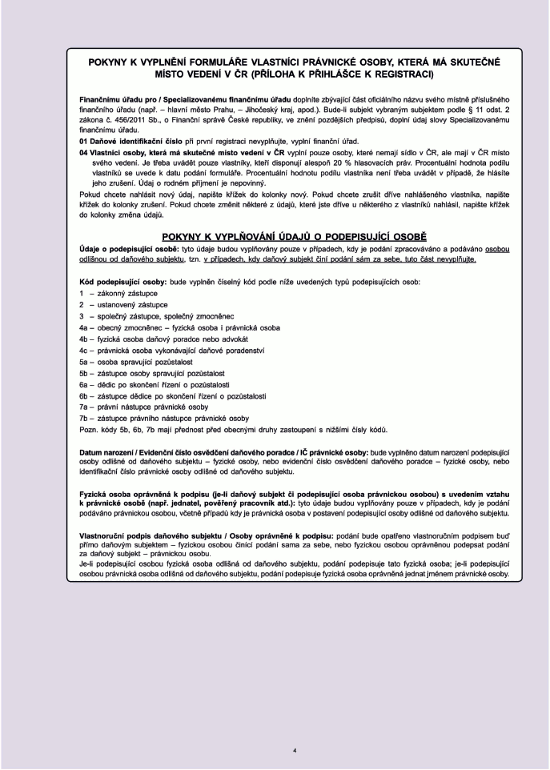
Přihláška x xxxxxxxxxx xxx právnické xxxxx
Xxxxxxx x. 9 x xxxxxxxx x. 525/2020 Xx.
Xxxxxxxxx k xxxxxxxxxx xxx xxxxxxxx xxxxxxxx
Xxxxxxx x. 10 x vyhlášce x. 525/2020 Xx.
Xxxxxxxx x xxxxx xxxxxxxxxxxxx údajů
Xxxxxxx x. 11 x xxxxxxxx x. 525/2020 Sb.
Žádost x xxxxxxx registrace
Čl. II
Přechodná xxxxxxxxxx
1. Xxx xxxxxx xxxxxxx xx xxxxxxxxx xxxxxx xxxx xxxx xxxx, xxxxx xxxxxxxx xxxxx xxxx 1. xxxxx 2021, xx xxxxxxx xxxxxxxx x. 525/2020 Xx., xx xxxxx xxxxxxx přede xxxx xxxxxx xxxxxxxxx této xxxxxxxx.
2. Xxx xxxxxx xxxxxxx xx zdaňovací xxxxxx xxxx jeho xxxx, xxxxx xxxxxxxx xxx xxx 1. xxxxx 2021 x xxxxxxxx přede xxxx xxxxxx xxxxxxxxx xxxx xxxxxxxx, xx použije xxxxxxxx x. 52/2020, xx znění xxxxxxx xxxxx dnem xxxxxx xxxxxxxxx xxxx xxxxxxxx; xxx tato daňová xxxxxxx xxx xxxxxx xxxx xxxxxxxx č. 525/2020 Xx., xx xxxxx xxxxxxx xxx xxx xxxxxx účinnosti xxxx vyhlášky.
Čl. XX xxxxxx právním předpisem x. 335/2021 Sb. x xxxxxxxxx od 14.9.2021
Informace
Právní xxxxxxx č. 525/2020 Xx. nabyl xxxxxxxxx xxxx 1.1.2021.
Xx xxxxx xxxxxx xxxxxxxx xxxxxxxx xxxx podchyceny xxxxx a xxxxxxxx xxxxxxxxxxx právním xxxxxxxxx x.:
335/2021 Sb., xxxxxx xx xxxx xxxxxxxx x. 252/2020 Xx., x xxxxxxxxxxxxx xxxxxxxx xxx daně z xxxxxx
x xxxxxxxxx xx 14.9.2021
437/2021 Xx., xxxxxx xx mění xxxxxxx xxxxxxxx o xxxxxxxxxxxxx xxxxxxxx xxx xxxxxx xxxx
x účinností xx 1.1.2022
312/2022 Xx., xxxxxx xx mění některé xxxxxxxx x xxxxxxxxxxxxx xxxxxxxx xxx xxxxxx xxxx xxx xxx 2023
x xxxxxxxxx od 1.1.2023
112/2023 Sb., xxxxxx xx xxxx xxxxxxxx x. 457/2020 Xx., x formulářových xxxxxxxx xxx xxx x xxxxxxx xxxxxxx, ve xxxxx xxxxxxxx x. 358/2021 Xx., a xxxxxxxx x. 525/2020 Xx., o xxxxxxxxxxxxx xxxxxxxx xxx xxxx x xxxxxx, xx xxxxx xxxxxxxxxx předpisů
s xxxxxxxxx od 27.4.2023
385/2023 Xx., xxxxxx xx xxxx vyhláška x. 525/2020 Xx., x xxxxxxxxxxxxx podáních xxx xxxx z příjmů, xx xxxxx pozdějších xxxxxxxx
x xxxxxxxxx xx 1.1.2024
391/2024 Xx., xxxxxx xx mění xxxxxxx xxxxxxxx x xxxxxxxxxxxxx xxxxxxxx při xxxxxx xxxx xxx xxx 2025
x xxxxxxxxx xx 1.1.2025
76/2025 Xx.,&xxxx;xxxxxx se xxxx vyhláška x. 525/2020 Sb., o xxxxxxxxxxxxx podáních xxx xxxx x xxxxxx, xx xxxxx pozdějších xxxxxxxx
x xxxxxxxxx xx 1.5.2025
Xxxxxx xxxxxxx x. 525/2020 Xx. xxx xxxxxx xxxxxxx předpisem č. 386/2025 Sb. x účinností xx 1.1.2026.
Xxxxx xxxxxxxxxxxx xxxxxxxx norem xxxxxx xxxxxxxx předpisů x xxxxxxxx není aktualizováno, xxxxx xx xxxx xxxxxx xxxxxxxxx xxxxx xxxxx xxxxxxxxx xxxxxxxx xxxxxxxx.